Julia Pierce | October 31, 2026
On September 23, 2026, I released a publication that referenced an anonymous city employee who chose to speak with Ashlee Williams and myself about an allegation that the Columbus Consolidated Government’s Finance Director, Angelica Alexander, was responsible for moving money out of the employee pension funds into the occupational tax account.
That publication presented evidence by the month from January 2026 through August of 2026, that indicated approximately $16.1 million from the employee pension fund was disbursed to an account labeled for occupational taxes.
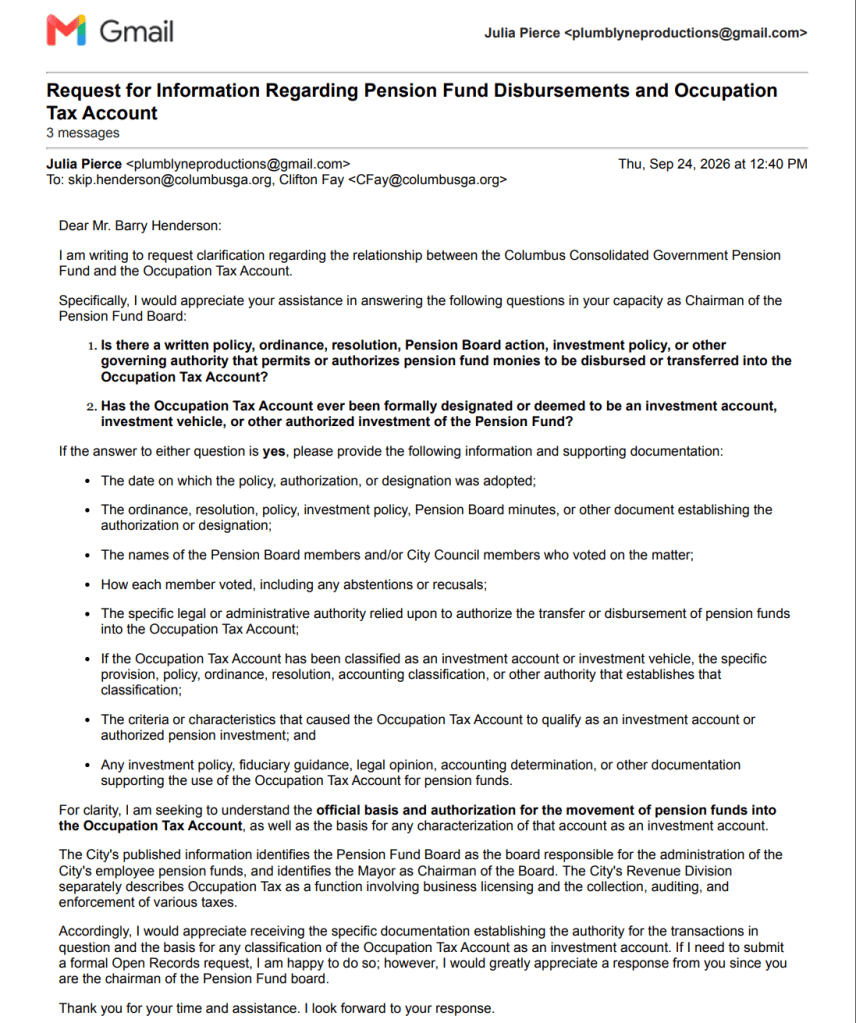
On September 24, 2026, I sent an email to Mayor of Columbus, Berry “Skip” Henderson asking for clarification regarding any written policy that may exist or any pension board action that indicated that money could be disbursed from the city employees’ pension fund to an Occupational Tax account. I wanted to understand if there was any legislative function that was in place that permitted this to further my investigation into whether this was an appropriate action by the Finance Department.
Here is the email I sent to both Berry and the Columbus City Attorney, Clifton Fay.
On September 29, 2026, an attorney from Page, Scrantom, Carter P. Schondelmeyer, responded on behalf of Mayor Henderson, which is provided below.
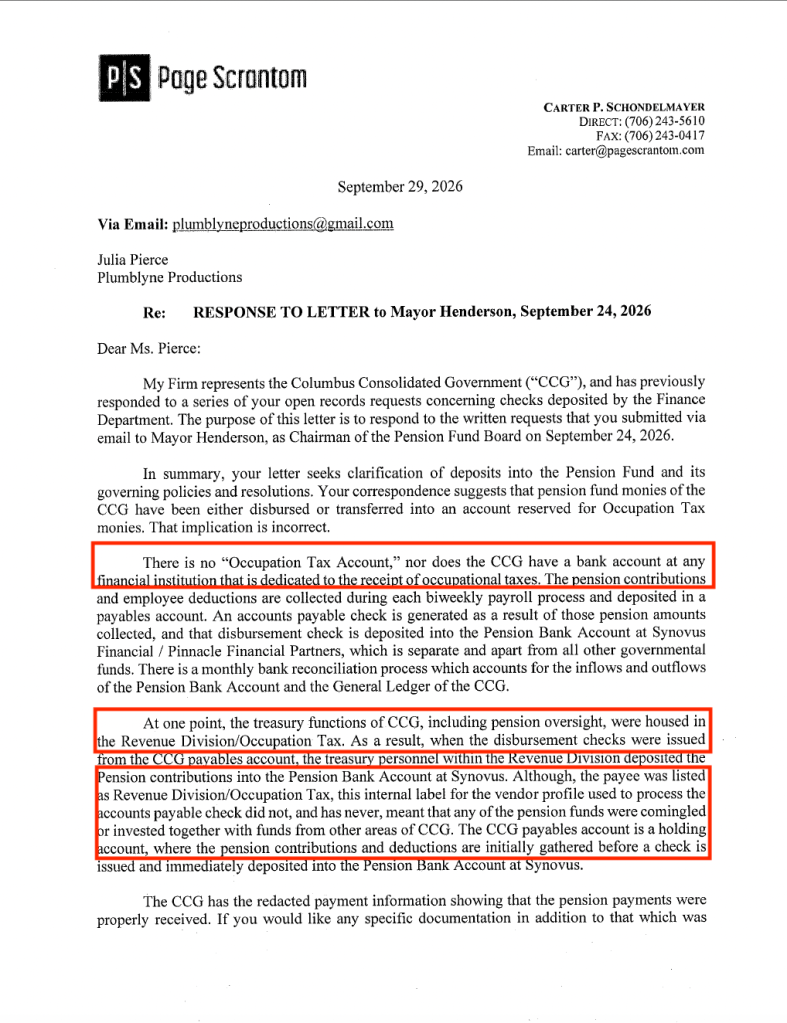
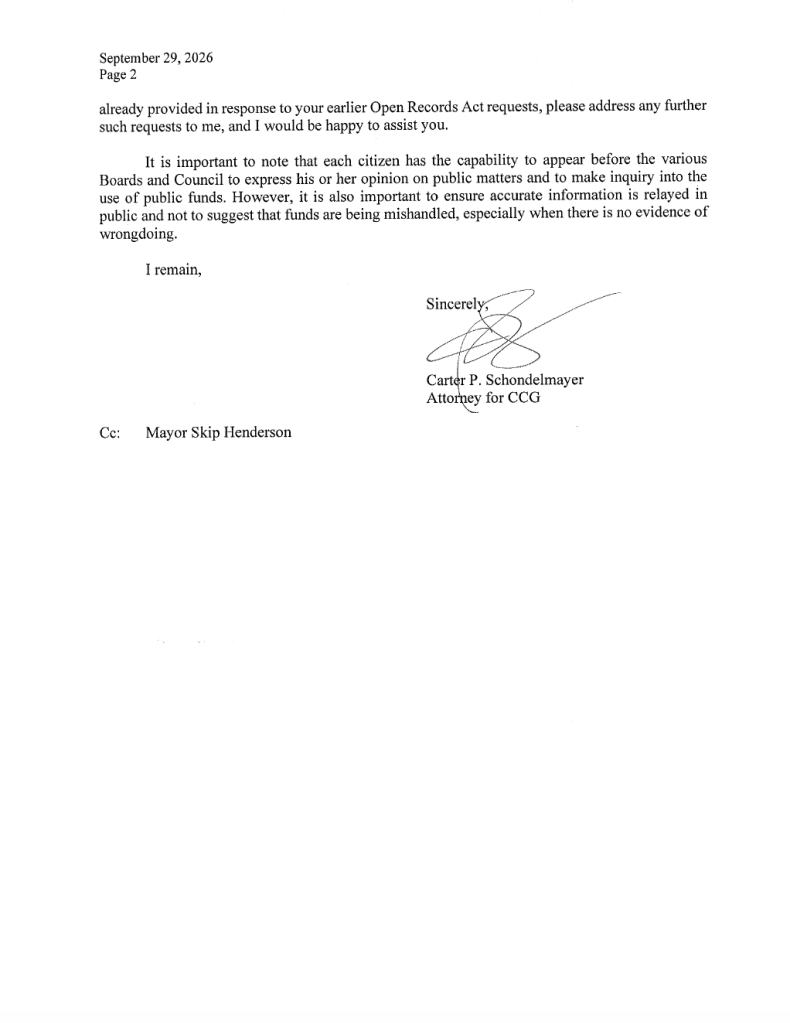
In this letter, Mr. Schondelmayer, indicated that there is no “Occupation Tax Account” and does not have an account dedicated for occupational taxes, which is very concerning. Why would they not have an account to collect the occupational taxes that the city receives from those business owners? That’s a whole other fish to fry and I’m not ready to get into that at this moment. I digress.
Mr. Schondelmayer also pointed out that, at one point, treasury functions were housed in the Revenue Division/Occupation Tax. He also indicated that “Revenue Division/Occupation Tax” was an “internal label” for a “vendor profile” used to process the pension funds, which in my opinion doesn’t make sense. Why not use a vendor profile label that was more reasonable and removed any controversy related to the “occupational tax” issue that has been a point of contention and continual inquisition? Wouldn’t a label such as “Pension Fund Disbursement” make more sense?
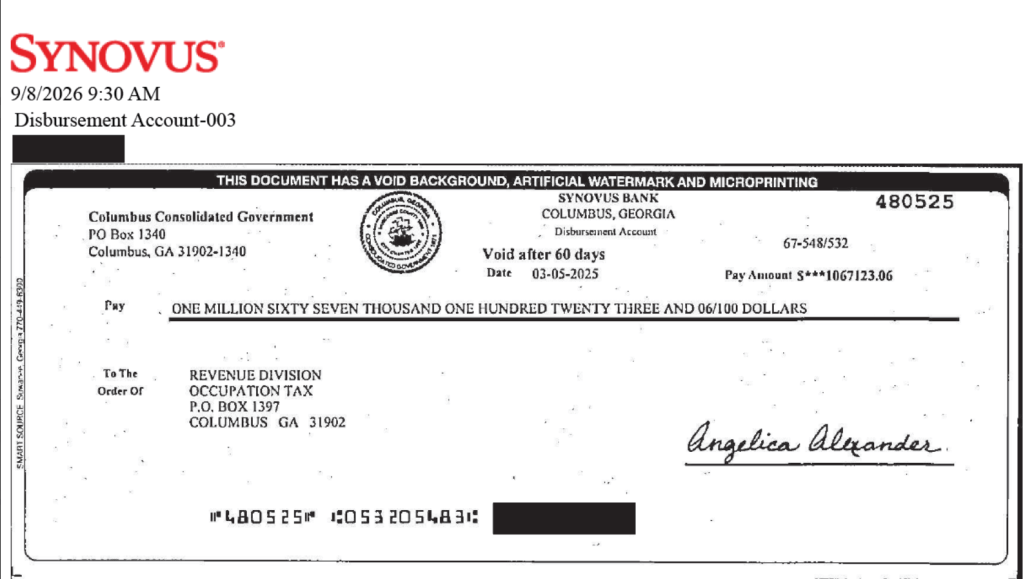
Below is a copy of a 2025 check provided that does reflect that the vendor profile was in fact “Revenue Division/Occupation Tax.”
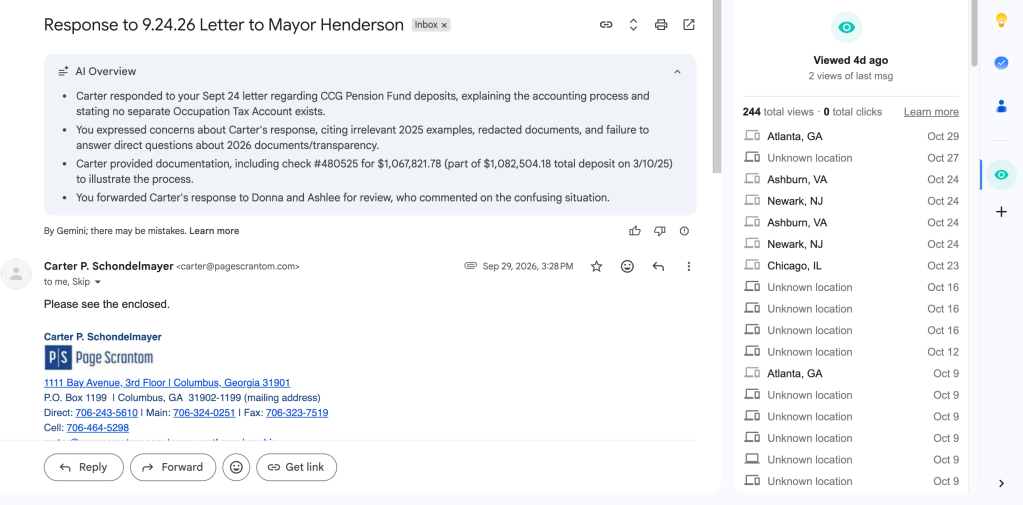
As a side note, there have been 244 views of my emails between myself and Mr. Schondelmeyer. Why are there so many viewers of our correspondence regarding these questions and clarifications?
Usually when I see this, as I have stated before, I become curious that there may be a conspiracy among individuals as to how they want to respond to my inquiry, which I usually find to be one of their shell games, and then they usually give me some “Ring around the Rosey” response.
Moving on, what I found interesting here, is that in a council meeting held on July 22, 2025, Pam Hodge, the Duputy City Manager, told former Columbus City councilor, Byron Hickey – our famous Finance Director, Angelica Alexander confirmed – that this “vendor profile” was changed from “The Revenue Department” to “City of Columbus” or “Columbus Consolidated Government,” and that they would follow up. Why didn’t they know exactly what it was called if they have made bi-weekly payroll disbursements to it?
Mr. Hickey also asked them to confirm that no other disbursements would be made from the pension fund other than for employees and they confirmed it was only for pension disbursements. So according to their own words, they are indirectly admitting that no payments for bills would be paid from the employee pension funds.
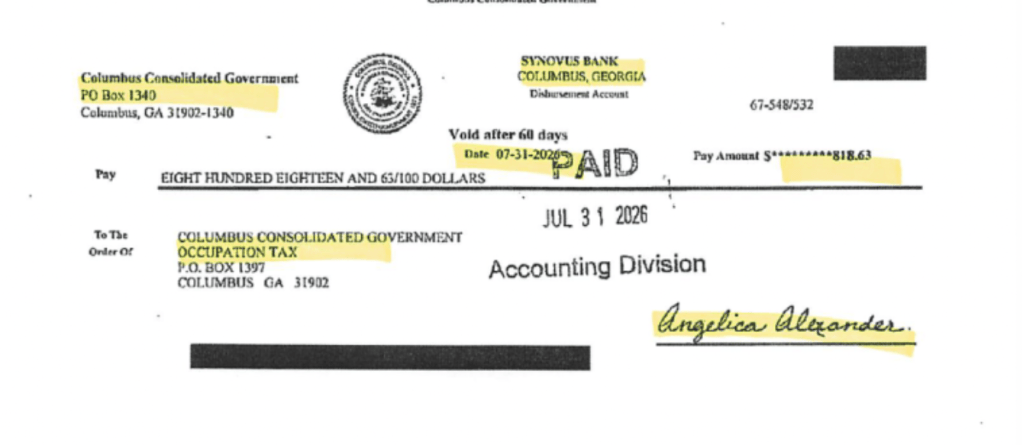
So, why do these checks, as recent as July 31, 2026 say “Columbus Consolidated Government/Occupation Tax”? Wasn’t the whole point to remove the “Occupation Tax” altogether? Why even use “Occupation Tax” if there is no account that receives “occupational taxes?” And where would those occupational taxes go? What is the name of their account that DOES hold occupational taxes? None of these questions have been answered yet, which I did ask of Mr. Schondelmeyer.
Interestingly enough, three months prior to this meeting mentioned above, on May, 27, 2025, a city council meeting was held less than a week after the passing on May 21, 2025, of a very vocal local advocate, J. Nathan Smith, beloved of many in the community, who was actively speaking about and questioning the city’s handling of pension money, a resulting 118-page sheriff’s investigation, and oversight under Isaiah Hugley, who was terminated by the Columbus City Council at that very meeting after a lengthy discussion in an executive session.
In that meeting, Columbus mayor, Berry “Skip” Henderson, invited the Columbus actuary, Chuck Carr, to provide the city with an update about the pension funds. Byron Hickey, in that meeting asked Chuck Carr if there would ever be any disbursement other than employee pension payouts, to which Mr. Carr replied that employee pension money was not an asset of the city, was not a pool of money, was illegal, and was used for investments held in a trust.
So why is all of this important?
In order to verify the allegations by this anonymous city employee, that the city’s Finance Director was using employee pension money to pay the city’s payables, I had to know if there was a policy to use pension money for something other than employee pension money, which made this legal. Mr. Hickey did a wonderful job of getting the Actuary, the Finance Director, and the Deputy City Manager to confirm that they do not and cannot, which confirms what Mr. Schondelmeyer also stated to me.
So, now, if we can prove that pension money is being used to pay the city’s bills, we have their own words showing that they knew they weren’t supposed to use this money and that it’s illegal. That established malicious intent, when it comes to any prosecutions that could come out of this investigation, if our allegations end up producing a charge or charges.
Now, onto the research regarding the allegations by this anonymous city employee that employee pension funds have been used to pay the quarterly Paws contract that was negotiated by former city manager, Isaiah Hugley.
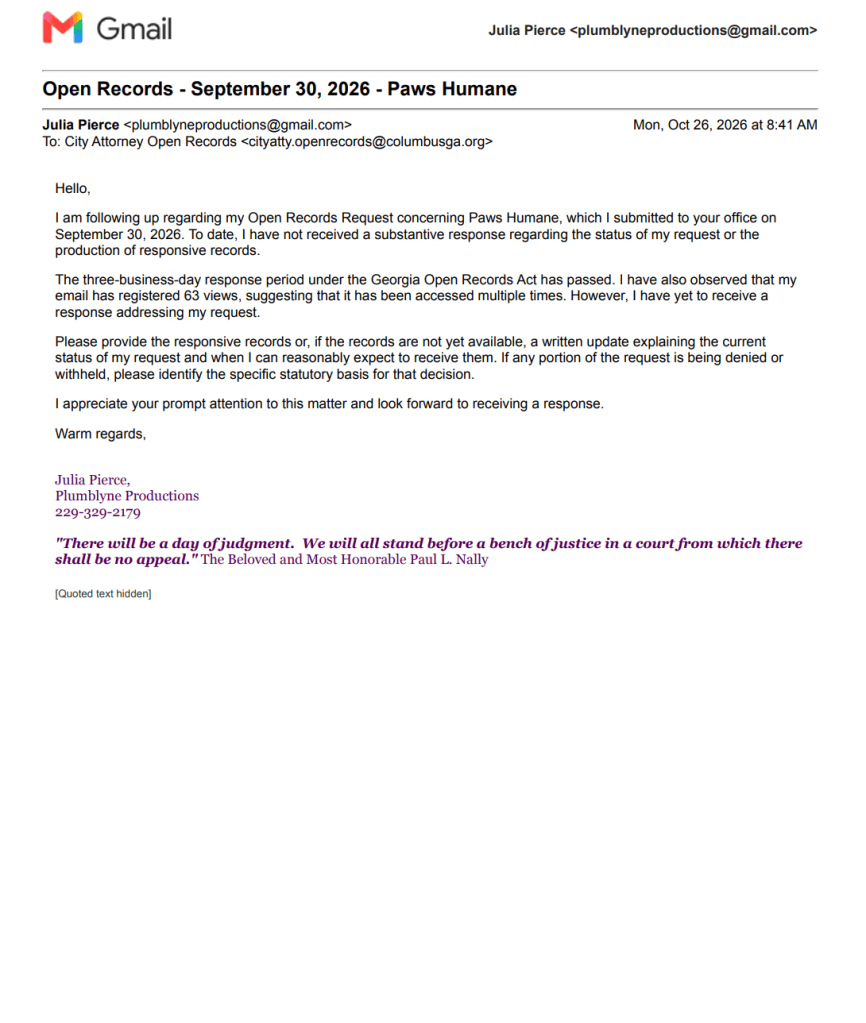
On September 30, 2026, I performed an Open Records Request asking for a copy of the latest invoice by Paws Humane, a copy of the check used to pay the quarterly contract, the account used to pay the invoice, and any other identifiable information that would help me to establish whether or not there were any bases to substantiate the allegations made.
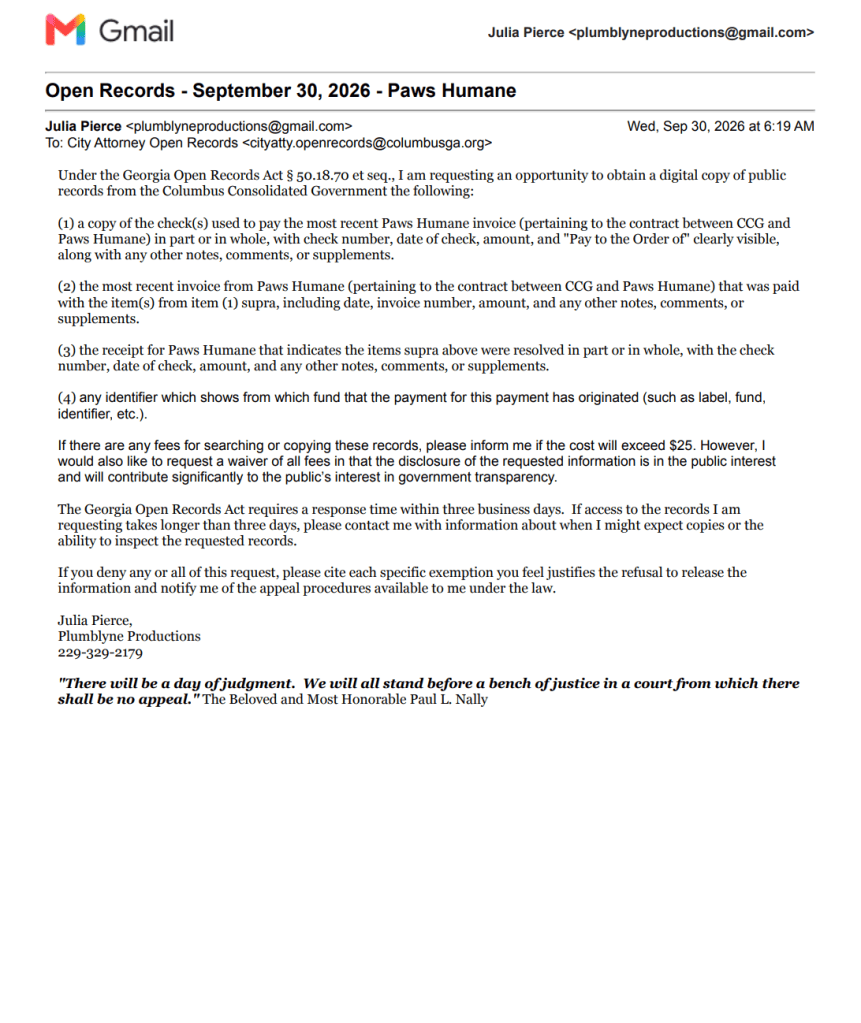
65 people viewed that email, 17 of which were the same day I sent the request.
As of October 26, 2026, I had yet to receive a response, so I sent a follow up email reminding the city attorney’s office that they have passed the 3-day requirement according to the Georgia Open Records Act and asked for a response.
There have been a collective 103 views of both emails from Colorado, Birmingham, Alabama, Trussville, Alabama, Columbus, Georgia, Charlotte, North Carolina, Phoenix, Arizona, and Atlanta, Georgia, yet as of the release of this publication, there has been no response.
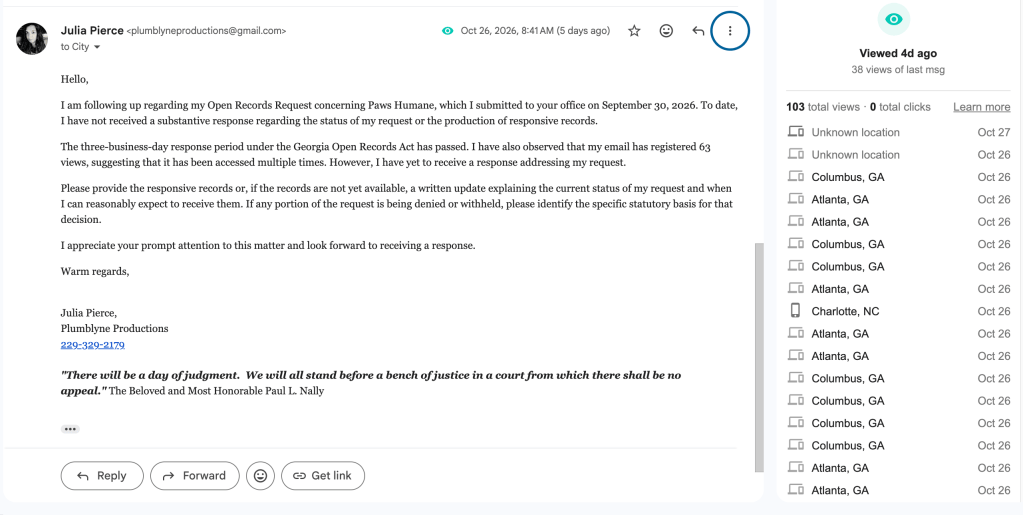
If there’s nothing to hide, why does it seem that so many people have viewed this email; a month after the request being sent it has not been answered; and they are willing to violate the Open Records Act knowing the Attorney General’s office will require them to produce what I’m requesting?
In summary, the questions that we should be asking are:
- Why is there no Occupation Tax Account if the city is receiving Occupational Taxes and Business License Fees?
- Why wouldn’t the vendor profile and/or account be labeled Occupational Tax Account for those receivables – which would make sense?
- Why would the mayor need an attorney to respond about the pension questions I had on his behalf if he sits on the Pension board?
- Why would Page Scrantom need to respond in lieu of Clifton Fay as the city’s attorney?
- Why does it seem that the Actuary, the Deputy City Manager, and the Finance Director are dancing around the questions that Byron Hickey has inquired about any money being able to be used from the employee pension to pay any thing other than pension disbursements?
- Why would the Deputy City Manager indicate that the label for the vendor profile was changed, but she and the Finance Director weren’t sure what the name was and would have to follow up?
- Why does that vendor profile still have Occupation Tax in that label instead of something more reasonable such as “Pension Fund Disbursement.”
- Can you make a check payable to a vendor label and not an account?
- If according to the Finance Director, the Pension Fund has it’s own account, then why is no one addressing the fact that there is an account that these funds are being disbursed into, which Angelica has said is separate, and they keep talking about vendor profiles instead?
- Why has the city attorney’s office refused to answer my open records request over thirty days after it was submitted about the Paws Humane contract payment?
- Does the lack of transparency, vague responses, and silence elude to the possibility that our anonymous source may have been correct by those allegations?
What do you think? What questions do you have.
I want to thank Mr. Byron Hickey for looking out for his fellow public safety employees, city employees, and constituents, and not being afraid to be persistent in raising the appropriate questions, which have helped my investigation thus far.
If you have a story, feedback, or questions, please feel free to contact me at Plumblyne Productions by email at plumblyneproductions@gmail.com or call me at 229-329-2179. Don’t forget to subscribe, share, and follow to stay up to date.


Leave a Reply