Julia Pierce, Ashlee Williams | September 23, 2026
In early August, a city employee, who has asked to remain anonymous, sat down with myself and Ashlee Williams regarding an issue within the city finances where the anonymous city employee alleged that money was being taken from employee pension funds and placed into the occupational tax account. This is the infamous occupational tax account where business licenses were the point of contention in October of 2023.
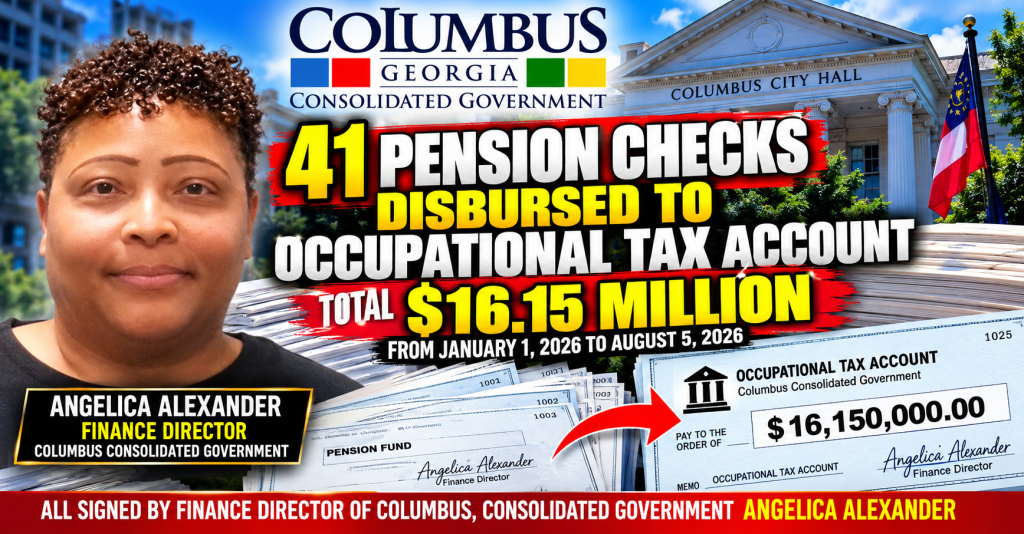
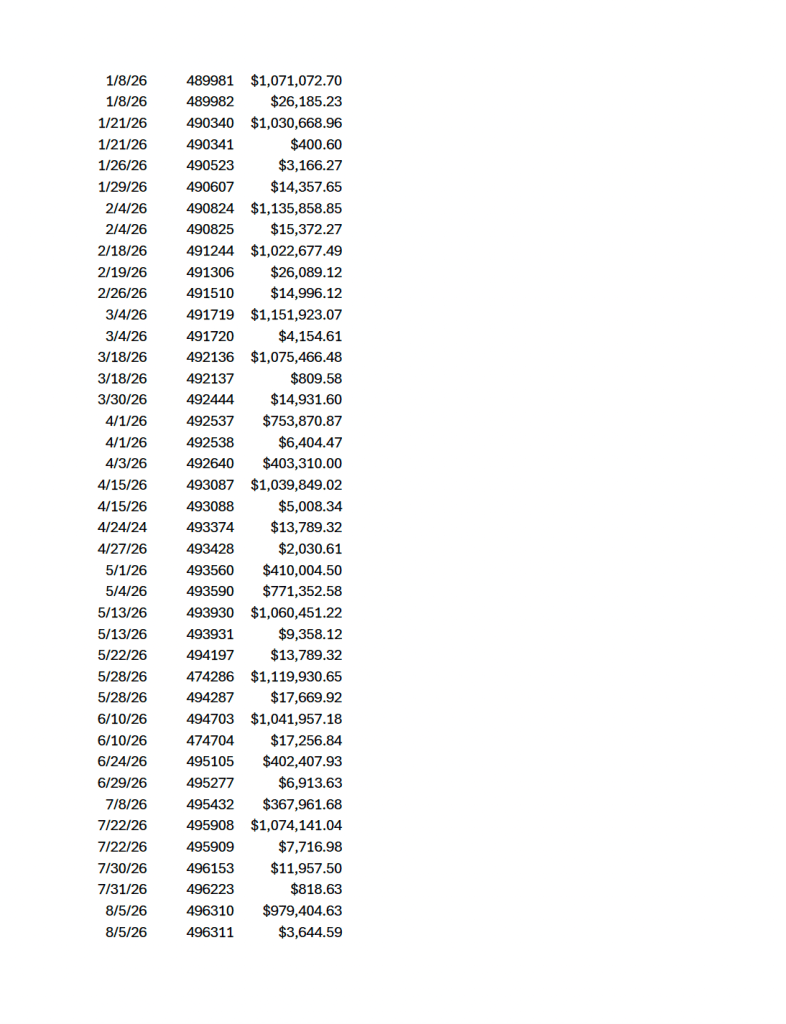
The anonymous employee wanted us to investigate. What we found out is that a representative from Page, Scrantom, Sprouse, Tucker, and Ford, on behalf of the city attorney’s office would return a large production of documents worth $130.41 of search, retrieval, redaction, and production that evidenced forty-one (41) checks from January of 2026 through August 5, 2026, in the amount of just over $16 million dollars, which were written from the employee pension disbursement account to the occupational tax account. It has been alleged that the city is using the Employee Pension Fund as petty cash to pay overdue payables and payables where the city has no revenue when those payables are due.
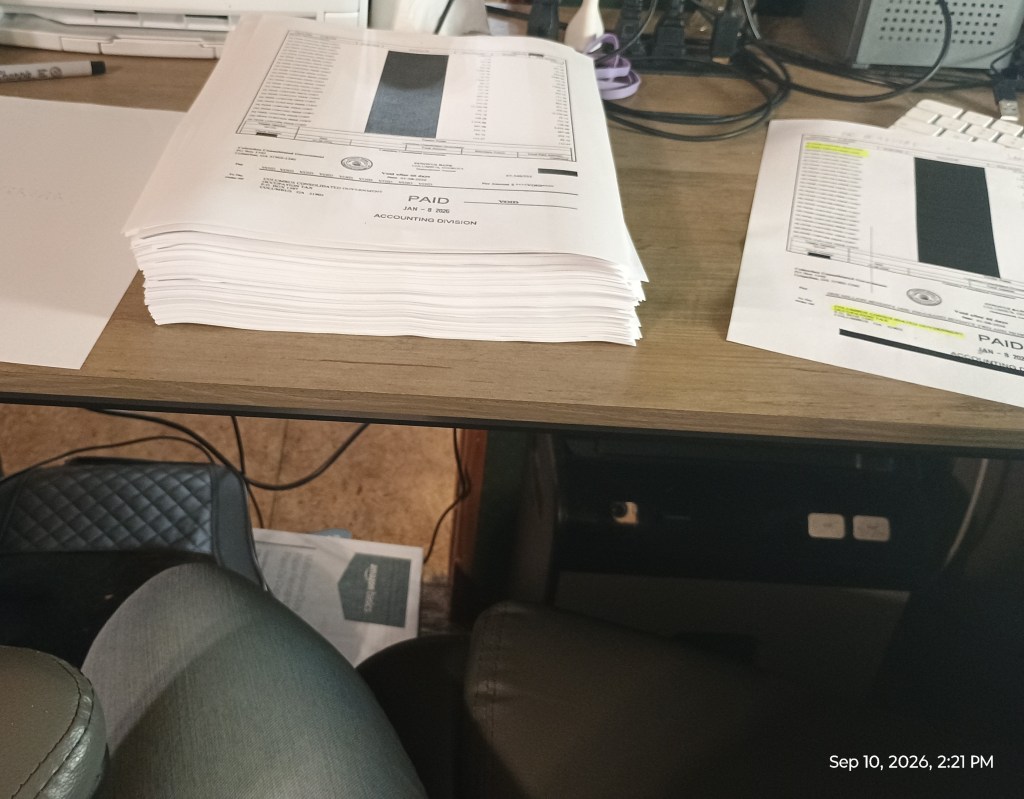
After printing each check and its accompanying itemized pension-related transactional disbursements, the sheer volume of the records became difficult to ignore. Some checks contained multiple pages of detailed transactions. In the case of 10 checks alone, each contained 20 pages of itemized transactions, with 25 transactions listed per page. That amounts to 500 individual transactions per check—or approximately 5000 itemized transactions across those 10 checks.
The volume of documentation is reflected in the image above. Printing the checks and their accompanying itemizations required nearly three-quarters of an entire ream of paper, or approximately 337 sheets. The sheer number of transactions, which amounts to 8,054 total transactions across 41 checks, raises questions about the nature, purpose, authorization, and accounting treatment of these pension-related disbursements into the Occupational Tax account.
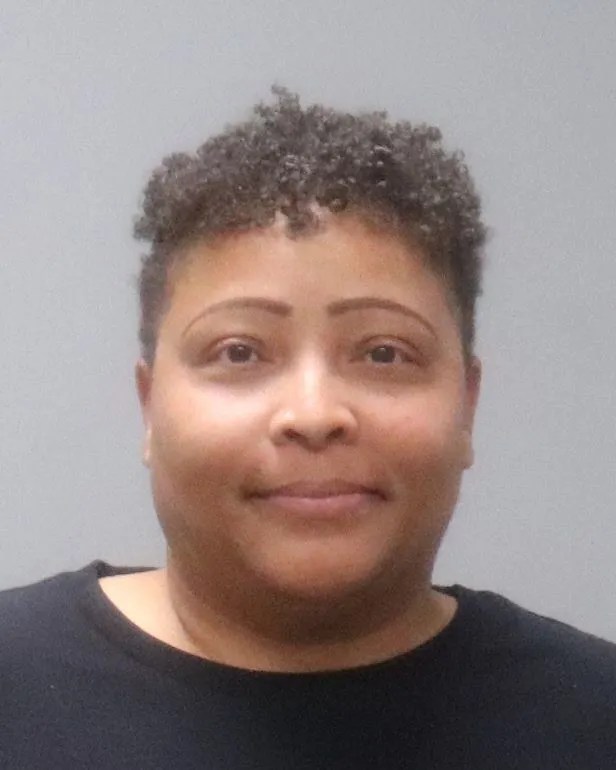
What I found the most interesting, is that Angelica Alexander, the Finance Director for Columbus Consolidated Government, signed every single one of these checks. For those who don’t remember, Angelica Alexander was arrested as a result of the sheriff’s investigation into the finance department’s questionable handling of the business licenses in 2025, that still remains a point of contention for most citizens in Columbus, Georgia.
Photo Credit: Muscogee County Sheriff’s Office
WHAT IS A PENSION FUND?
To understand the issue at hand, it is important that we know what a pension fund is.
A pension fund is a pool of money established to provide retirement benefits to eligible employees or beneficiaries. It may be funded through employee payroll deductions, employer contributions, investment earnings, and other legally authorized sources. These funds are generally subject to the terms of the governing retirement plan and applicable laws and are intended to be used for the payment and administration of retirement benefits—not as a general source of revenue for unrelated governmental purposes.
In her own words, as evidenced in the CCG TV YouTube video clip below, Angelica Alexander explains the Columbus Consolidated Government’s Pension Fund at a council meeting on July 22, 2025. She explains that there are four types of pension funds: (1) the General Government plan, (2) the Public Safety Plan, (3) the Major Disability Plan, and (4) the Death Benefit Plan.
WHAT IS AN OCCUPATIONAL TAX ACCOUNT?
To understand the issue at hand, we must also understand what an occupational tax account is.
An occupational tax account is a government account used to receive, record, and account for revenues associated with occupation taxes imposed on businesses and professionals operating within a local government’s jurisdiction. Under Georgia law, an occupation tax is a revenue-raising tax imposed by a local government on persons, businesses, partnerships, corporations, or other entities for engaging in an occupation, profession, or business. In Georgia, an occupation tax is commonly associated with what is often referred to as a business license or Occupation Tax Certificate. Accordingly, an account designated for Occupational Tax revenues would ordinarily be expected to contain and account for business-related tax revenues and associated fees, subject to the local government’s ordinances and accounting procedures.
According to an article, entitled Millions of dollars in jeopardy as Columbus leaders sort business license debacle written on November 2, 2023, Tim Chitwood wrote that “City Manager Isaiah Hugley and Finance Director Angelica Alexander told city councilors who demanded a report on license renewal issues in the city’s revenue division … The occupational taxes that division collects through business licensing generates millions for the city government’s general fund, growing from $15 million in 2019 to $18.8 million this year. An outline of the city’s operating fund for fiscal year 2024 estimated that revenue at $19.2 million, or 6% of the total.”
So, an occupational tax account in context of Columbus Consolidated Government is an account where Business License Revenue – and the taxes that get paid by those businesses – is received, and its funds then populate into the government’s general fund.
THE BACKSTORY
On August 26, 2026, a publication was released that detailed an Open Records Request to the City Attorney’s office for checks that would prove that large amounts of money were taken from employee pension funds and deposited into the occupational tax account. In that publication, the request that was submitted, the back and forth with the city attorney’s junior paralegal about the cost of production, and the amount of views that my emails were getting was presented. At that time there were 379 views of that email by city employees where this information was requested. As of the date of this publication, there have been 430 views.
From an insider, the reasoning for the back and forth, cost of production issues, and production issues themselves, are due to them “trying to figure out how NOT to give you this information.” This is important because this establishes intent, which is an important element needed in the legal realm to get a conviction on many crimes.
Why would the finance department and the city attorney’s office be working to figure out how NOT to give me this information if they aren’t doing anything wrong?
After the back and forth with the junior paralegal, I was contacted by a guy – literally, his name is Guy – from Page, Scrantom, Sprouse, Tucker, and Ford, with the 41 checks where employee pension disbursements were made into the occupational tax account. As a disclaimer, Guy was professional, courteous, attentive, and accurate in his responses and productions.
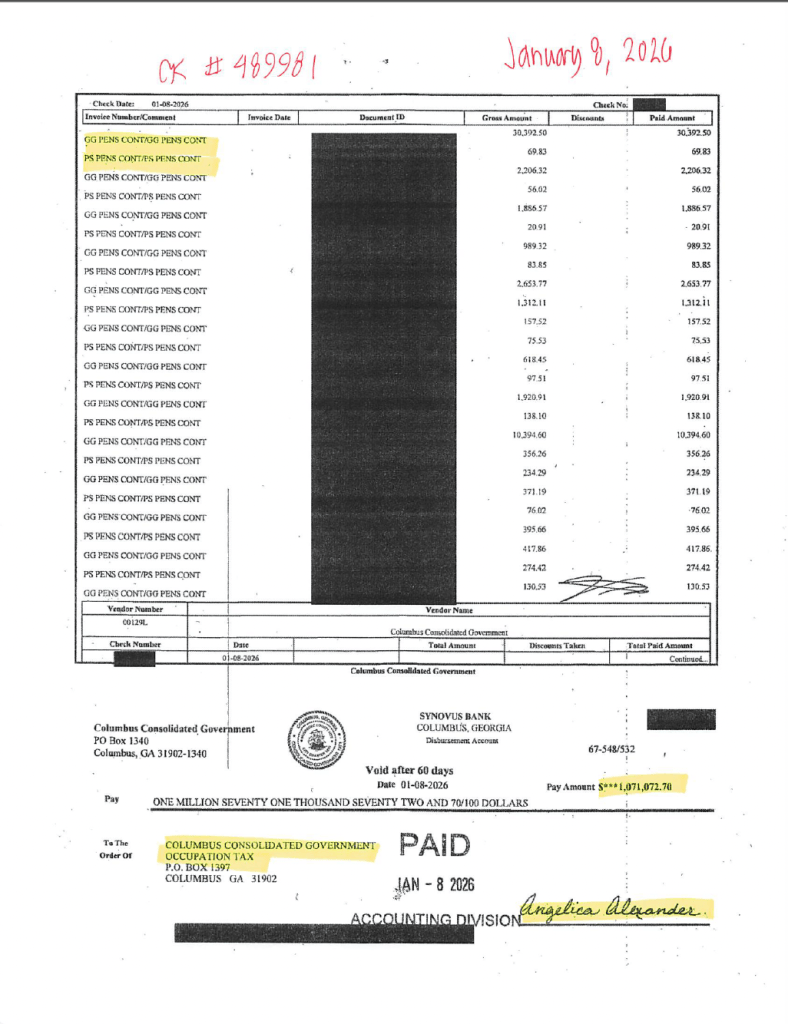
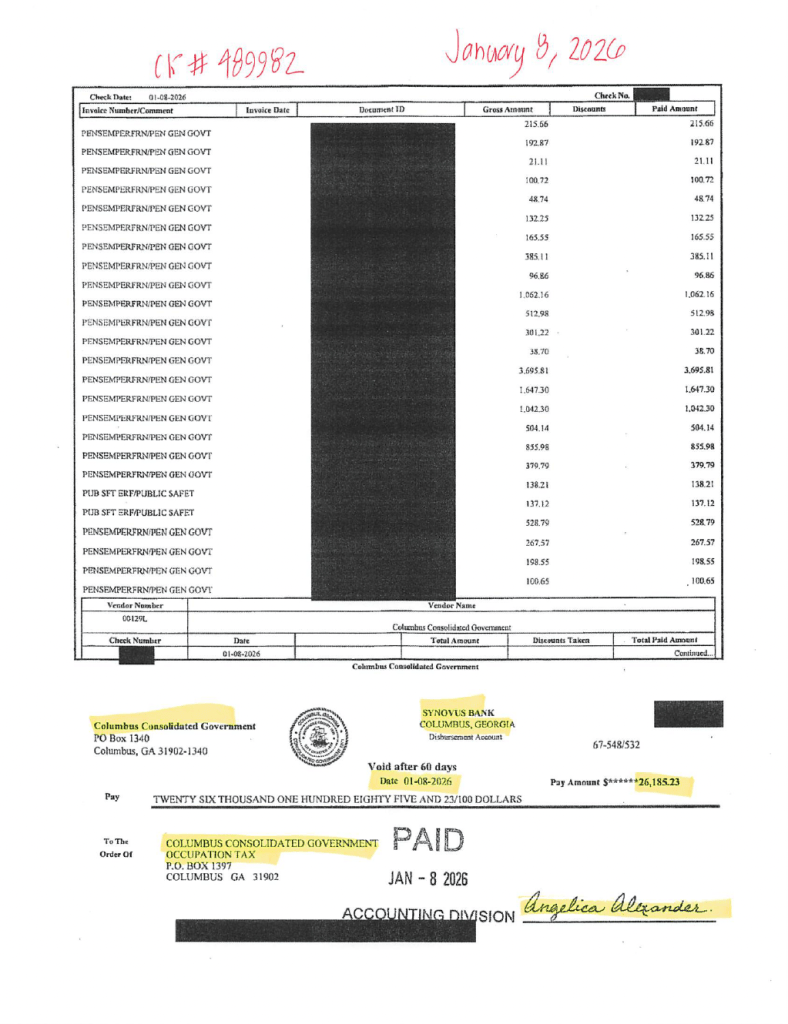
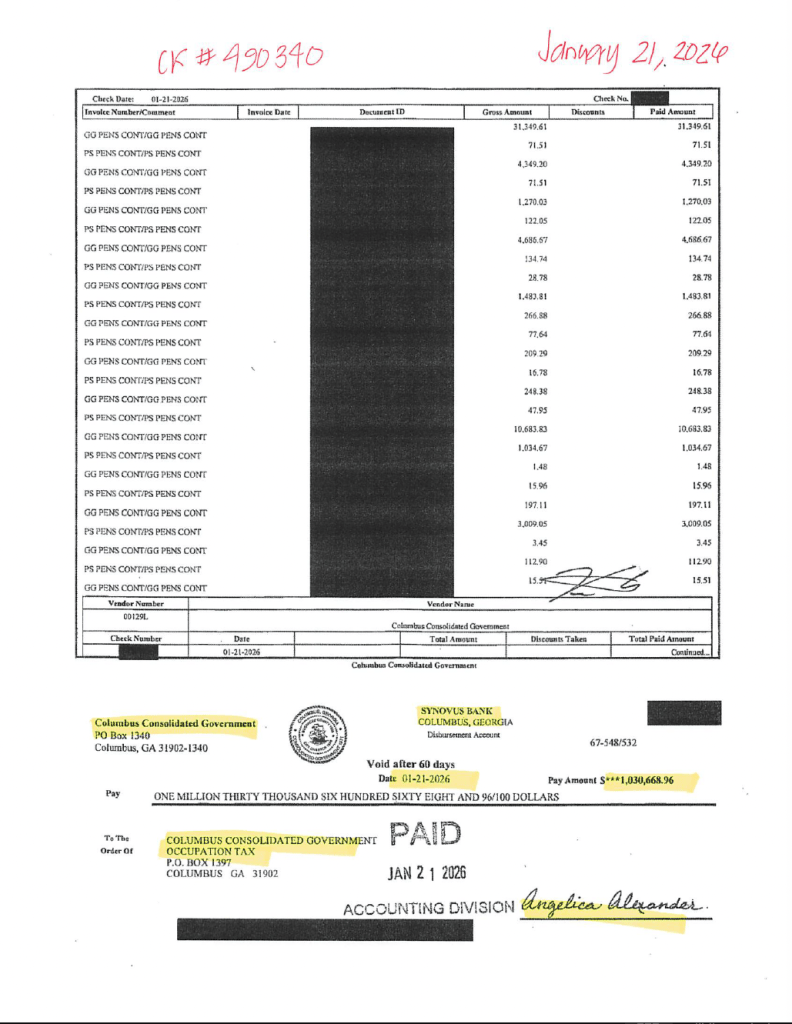
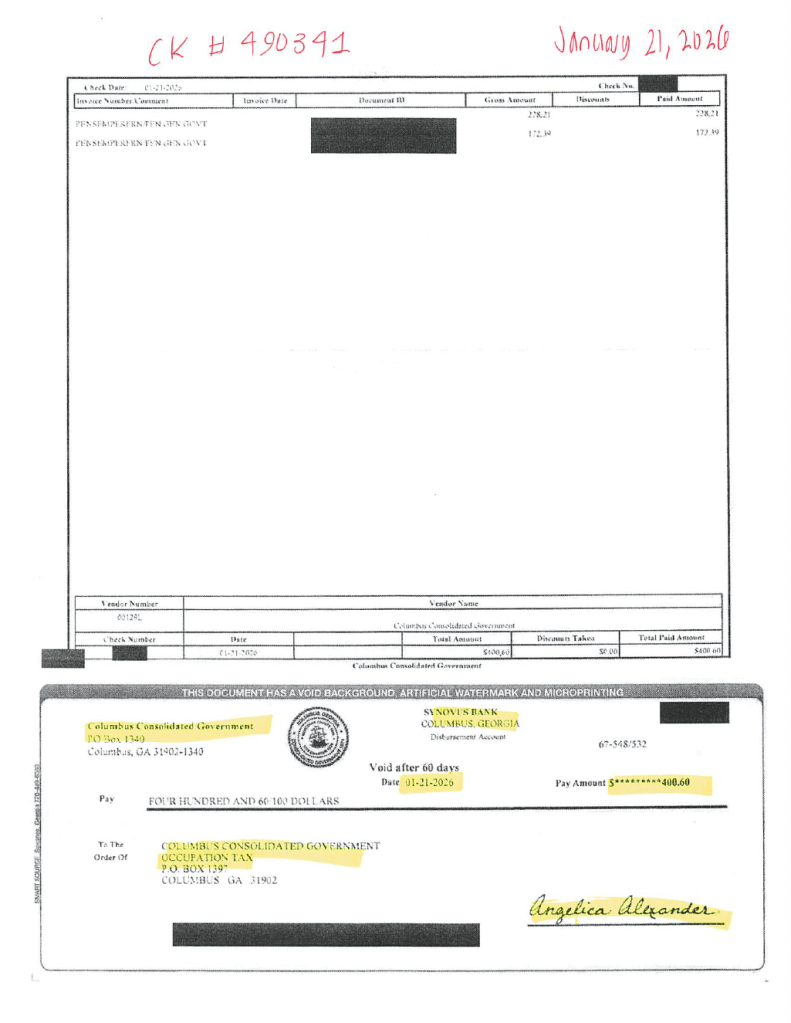
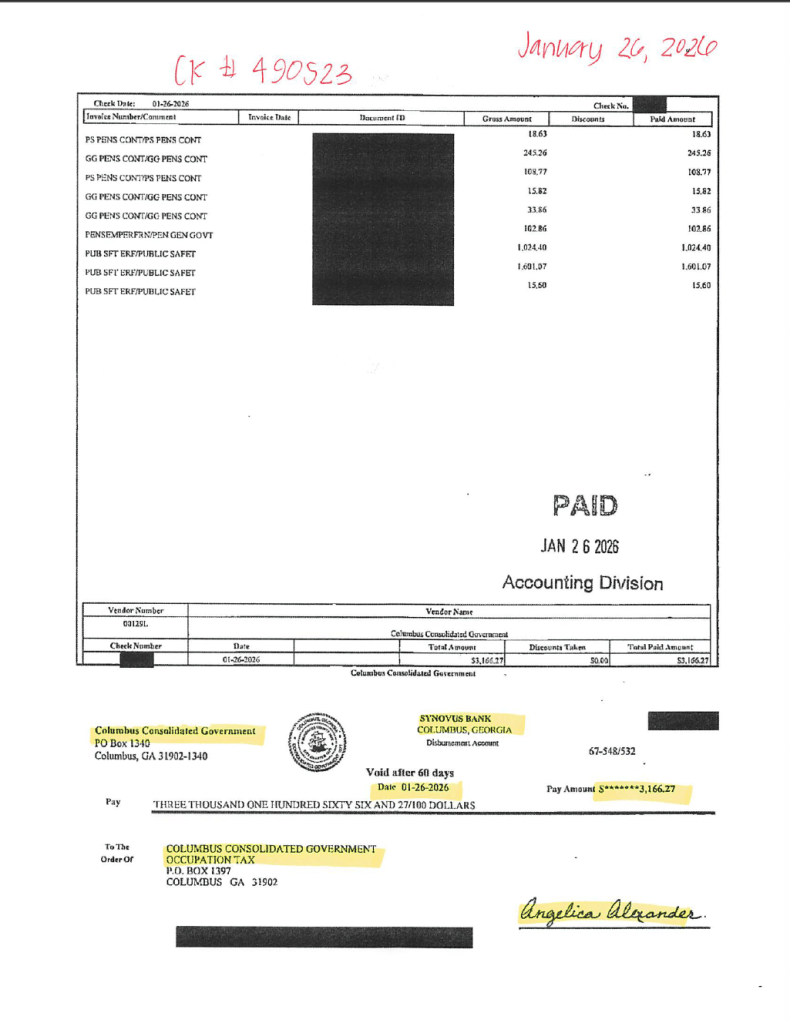
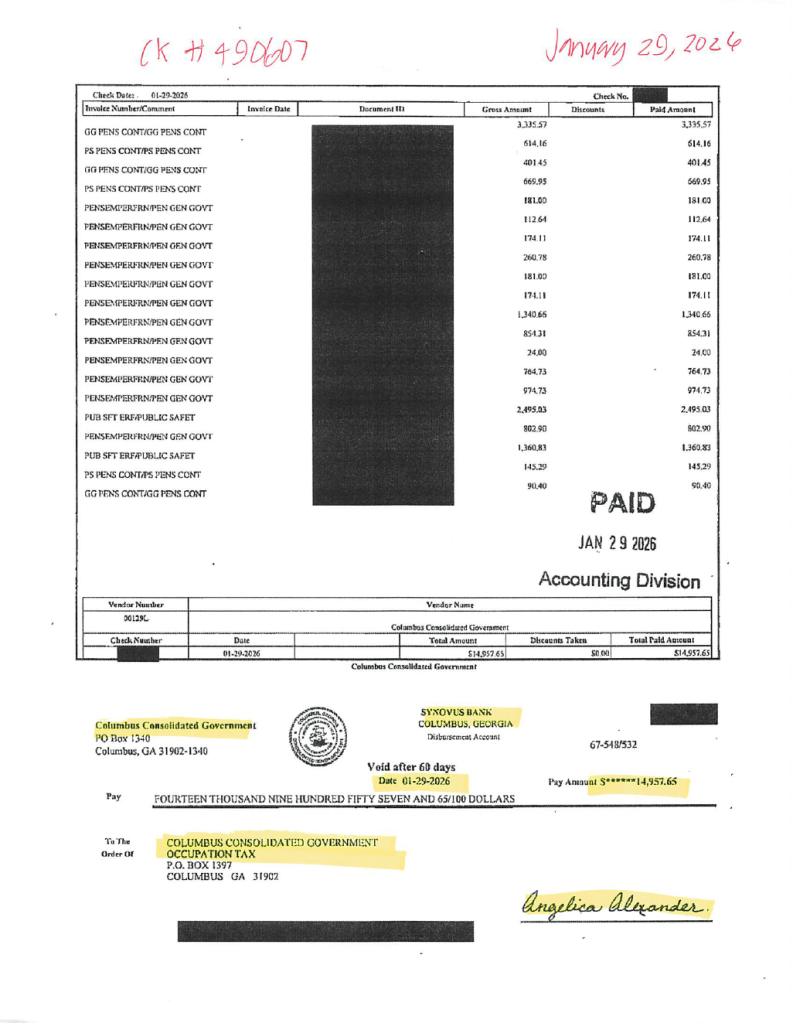
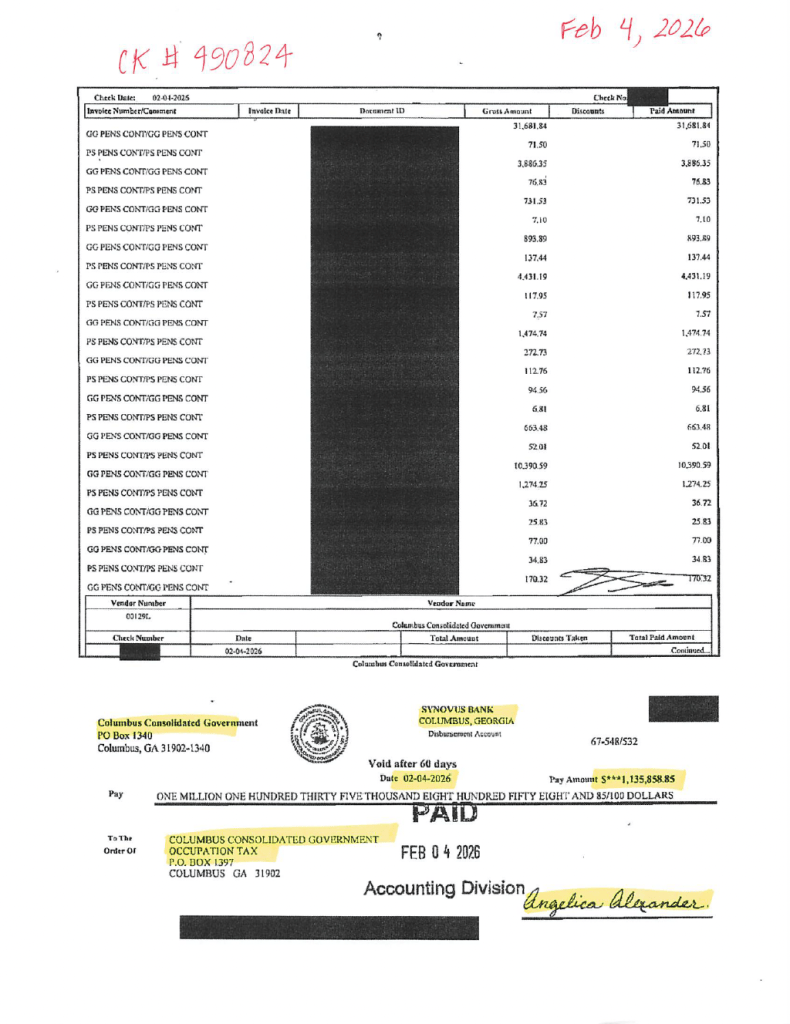
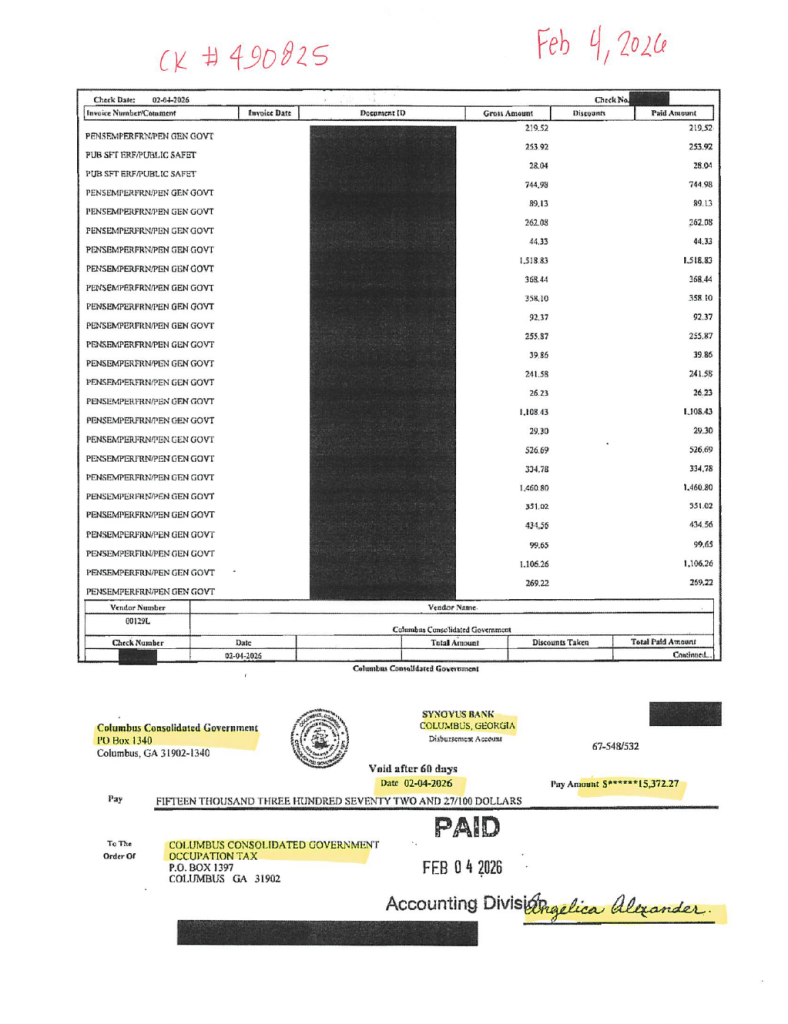
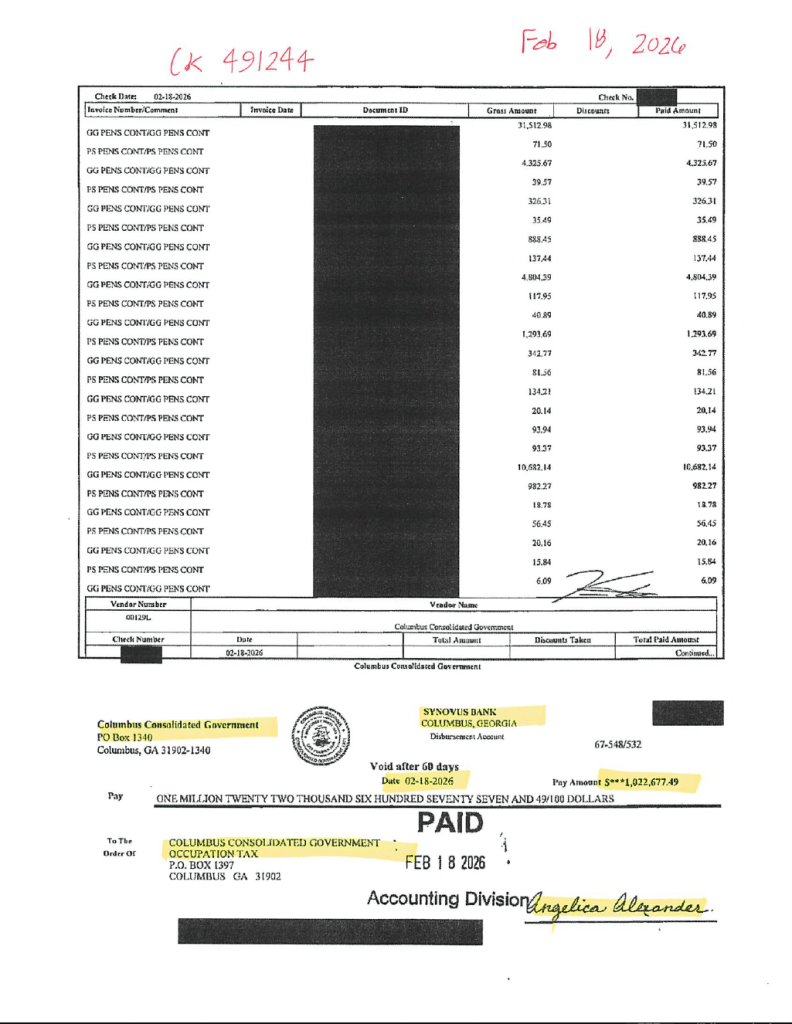
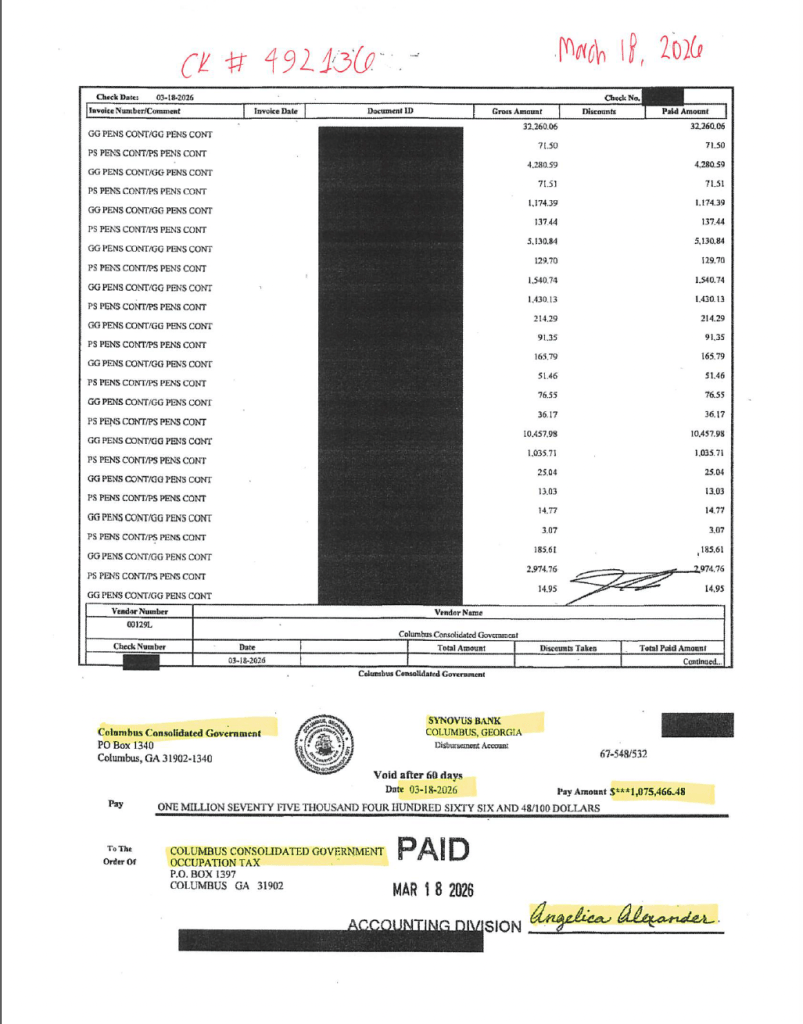
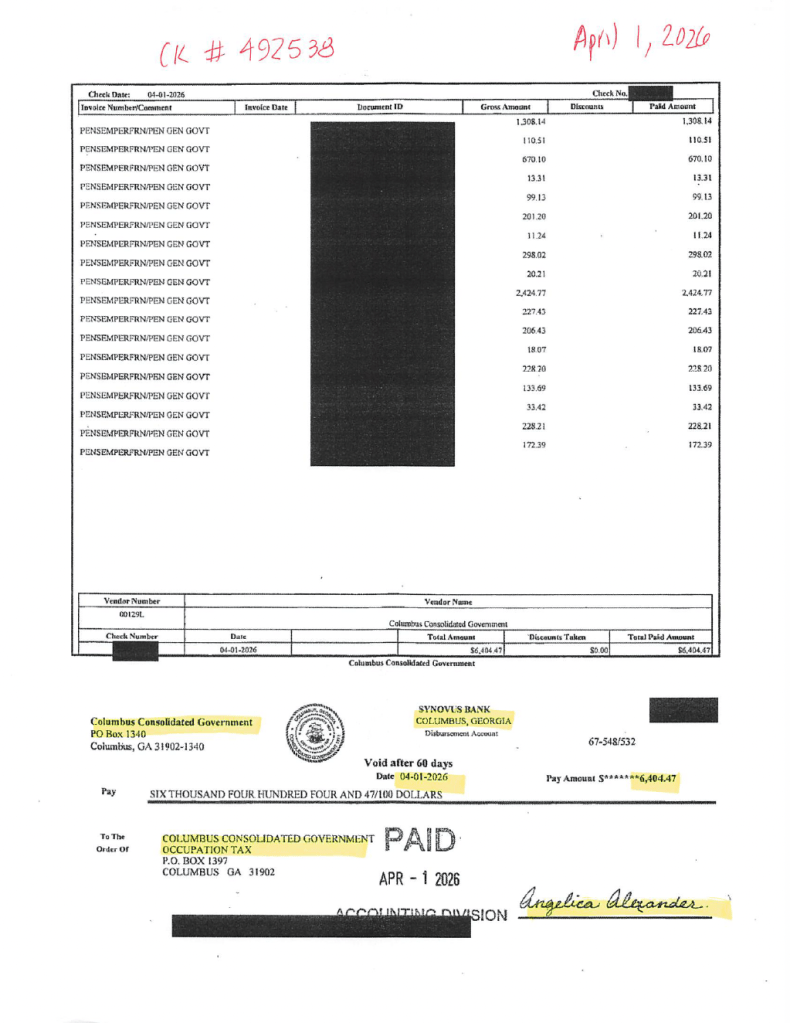
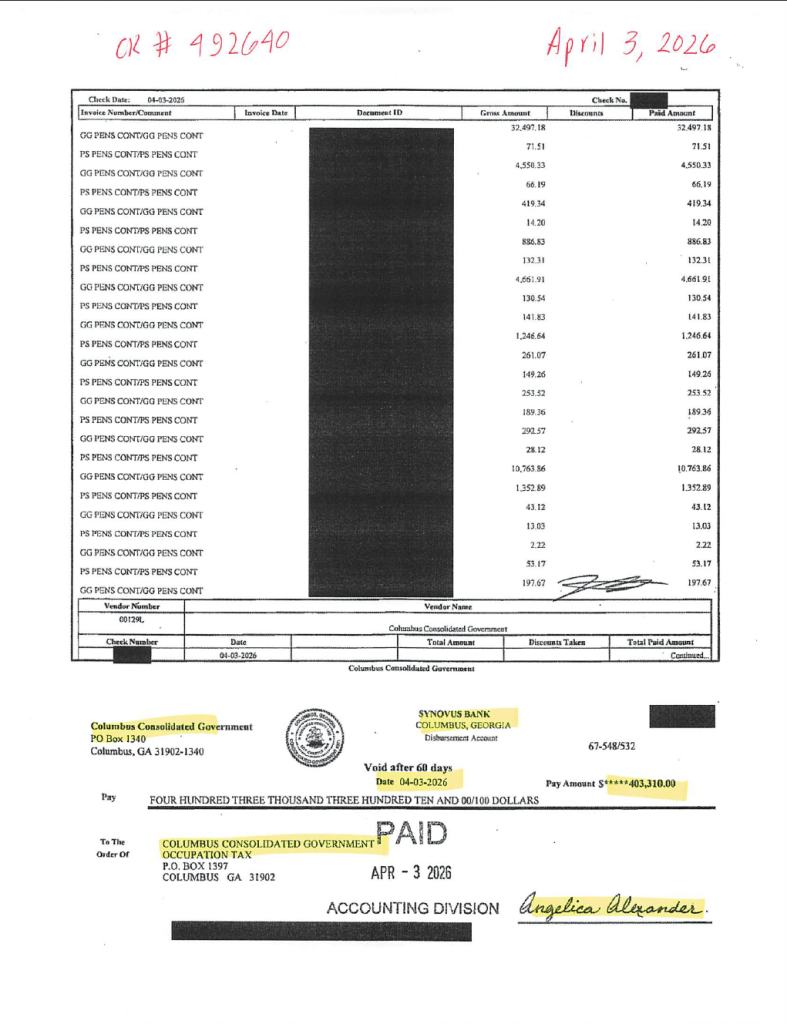
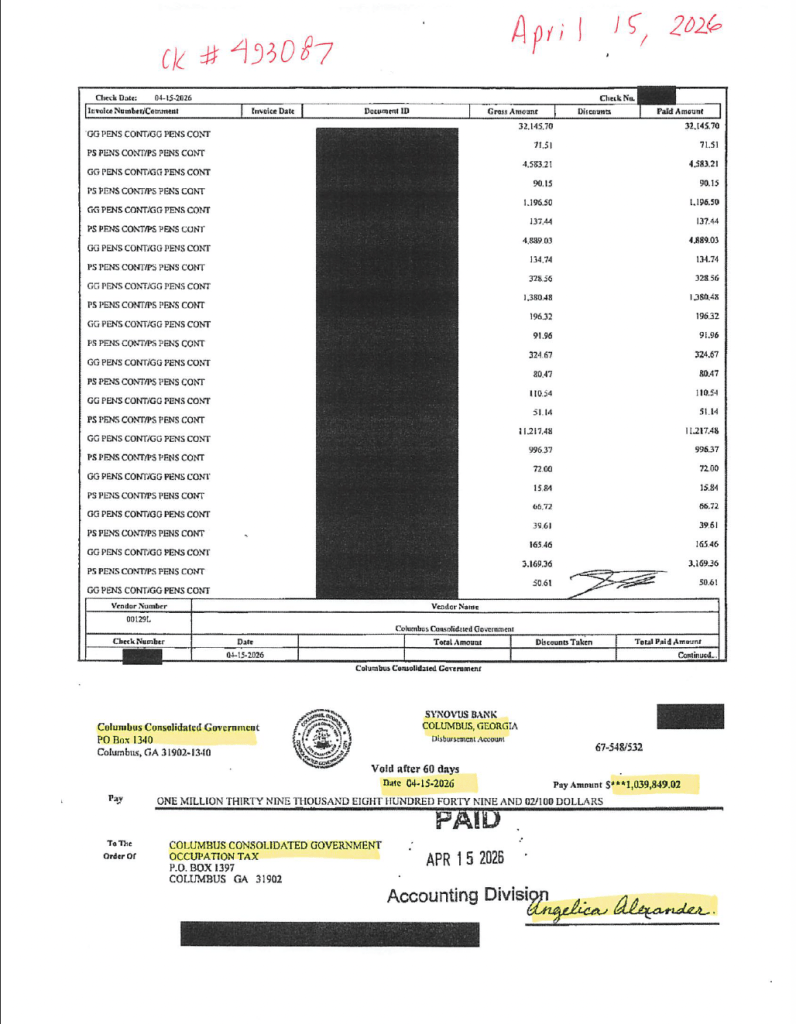
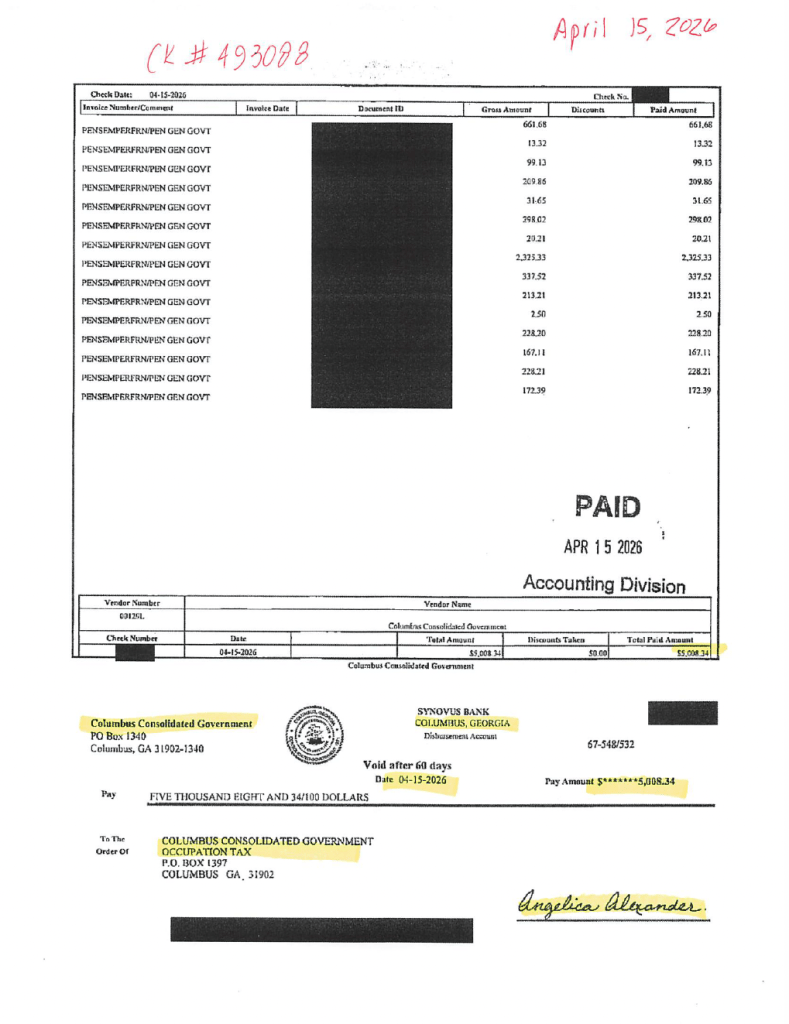
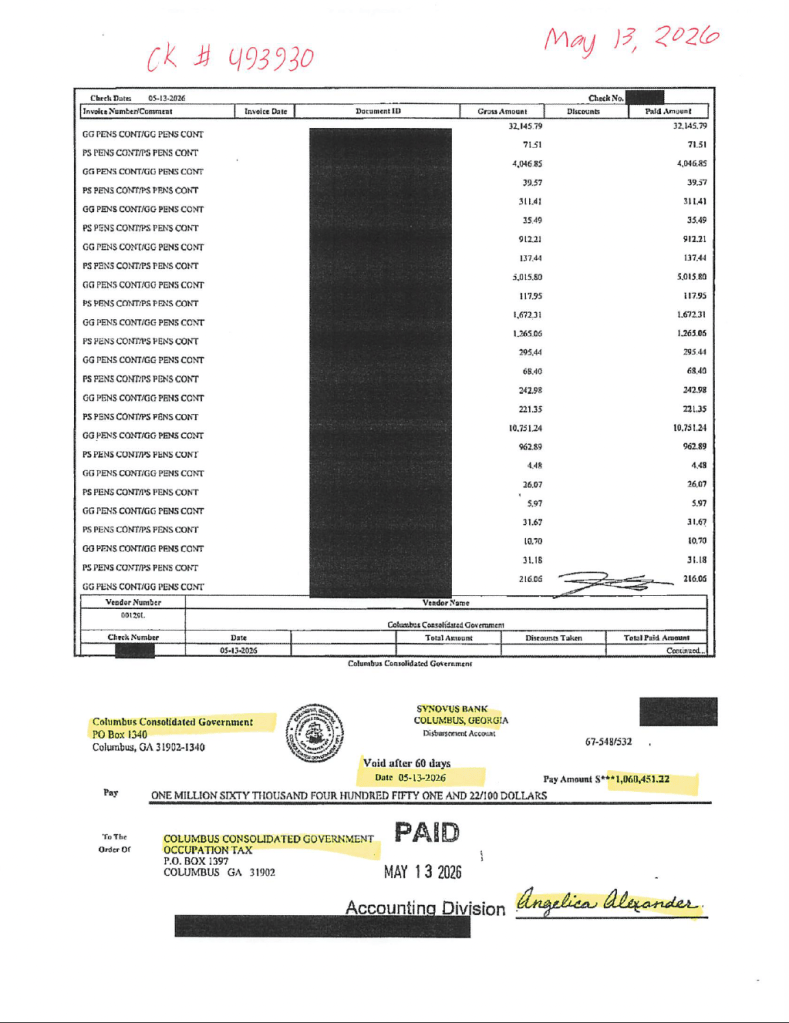
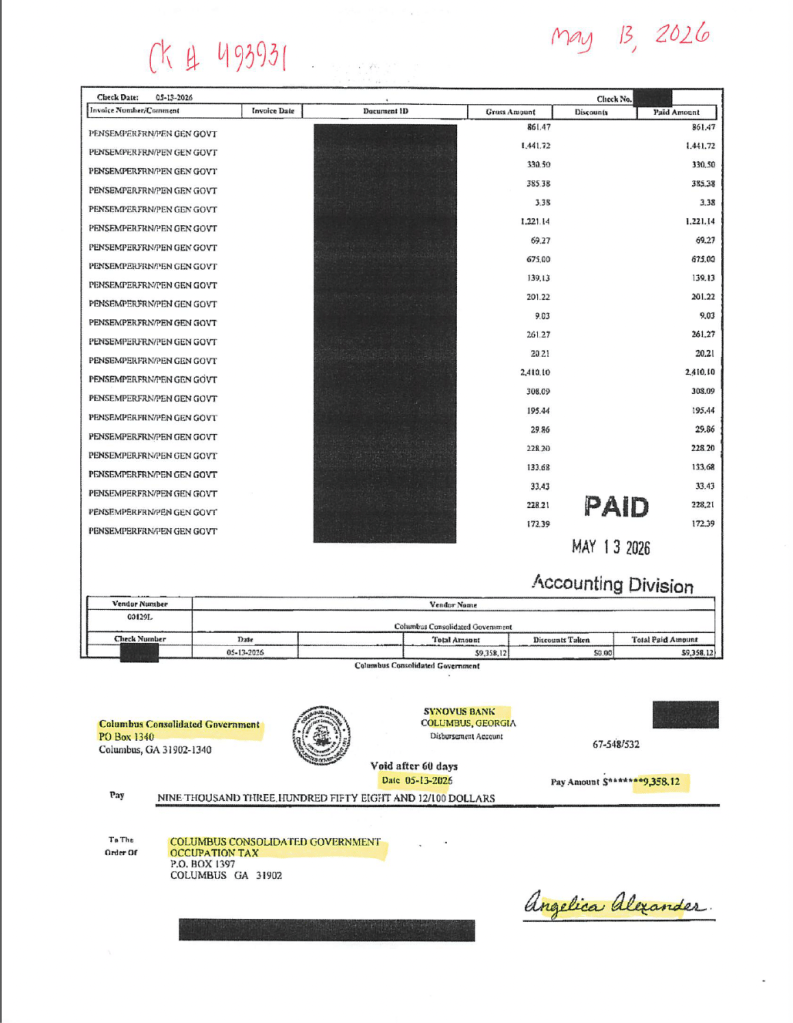
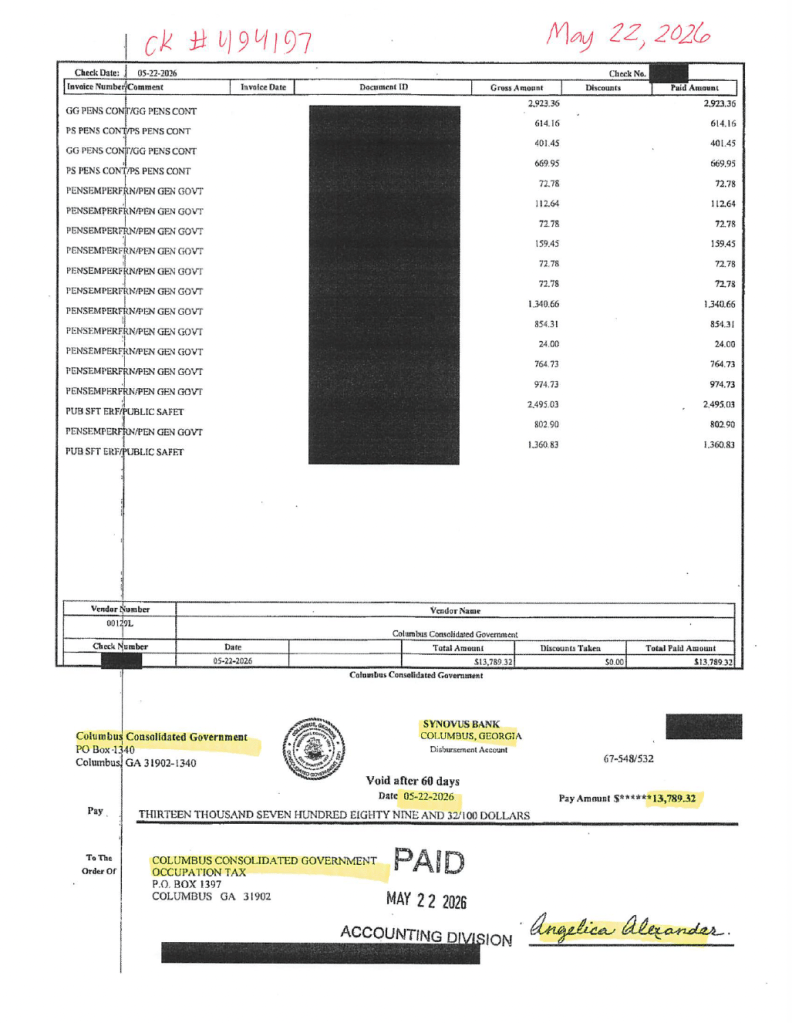
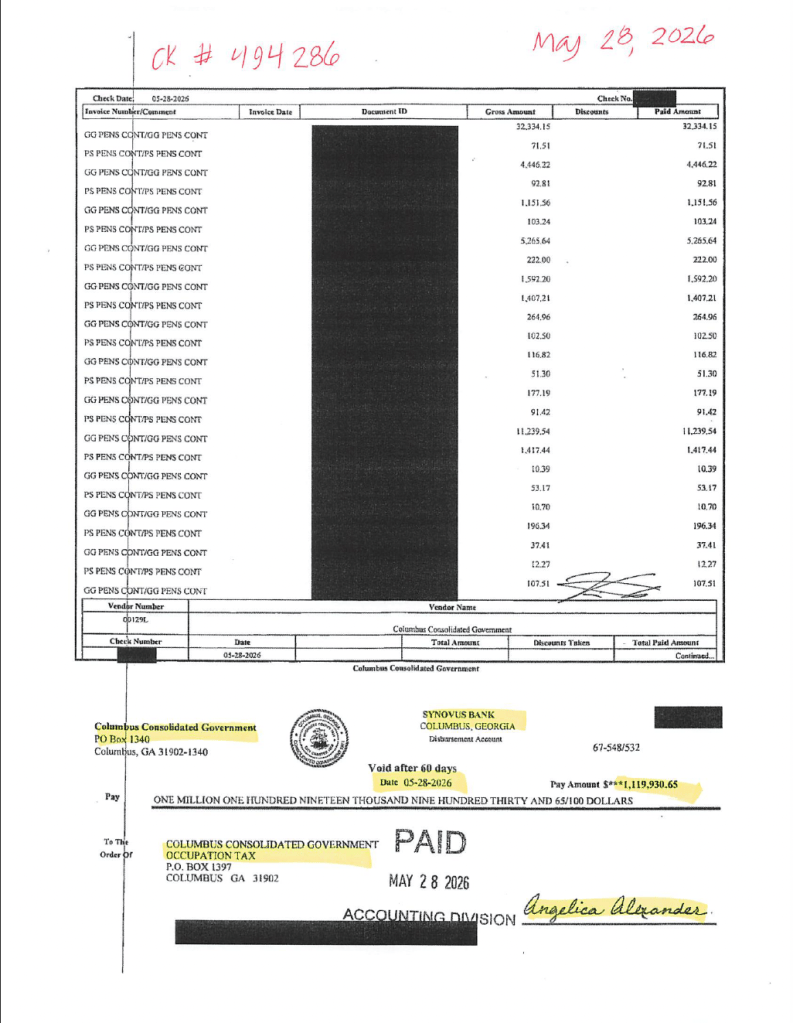
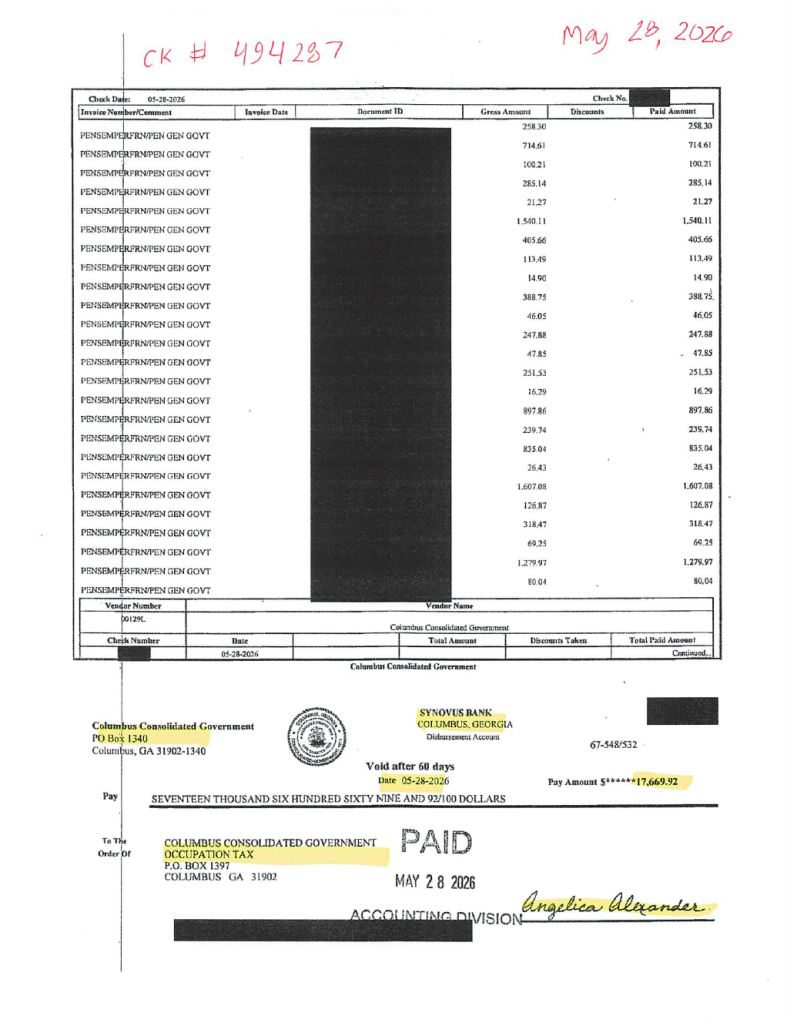
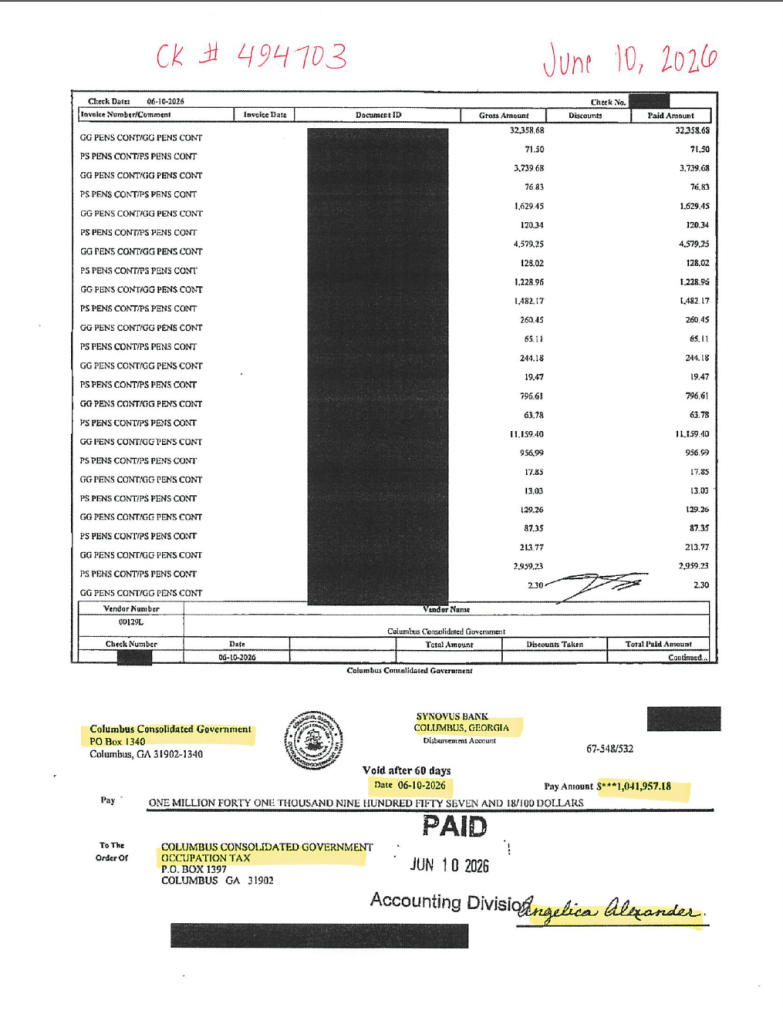
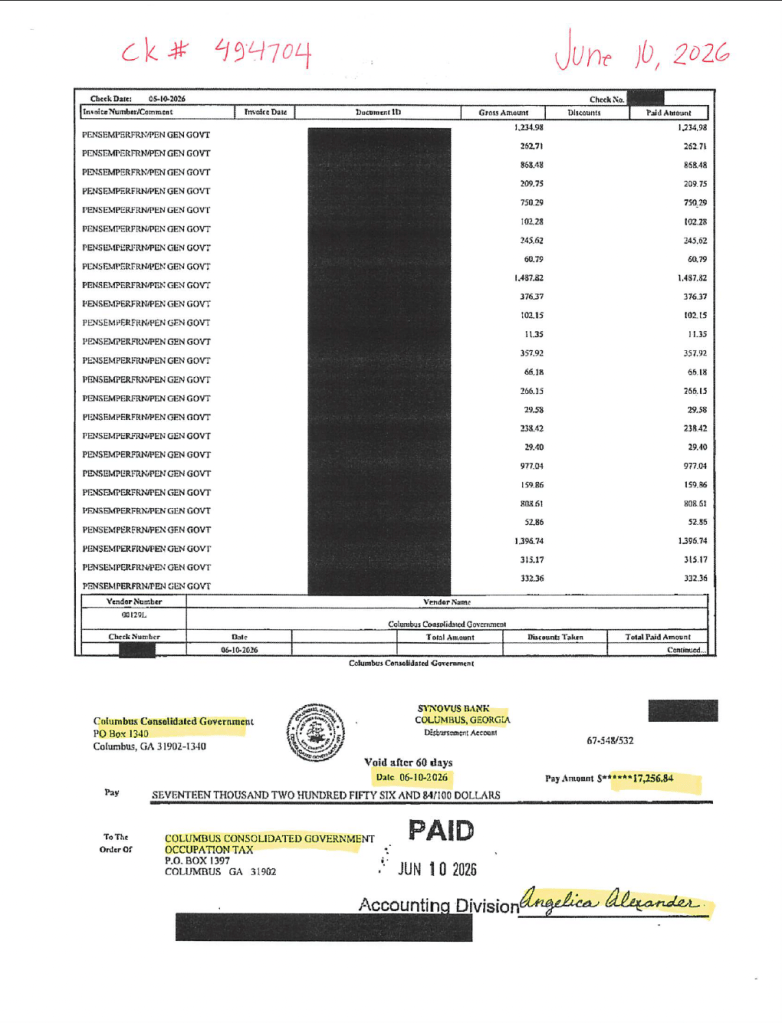
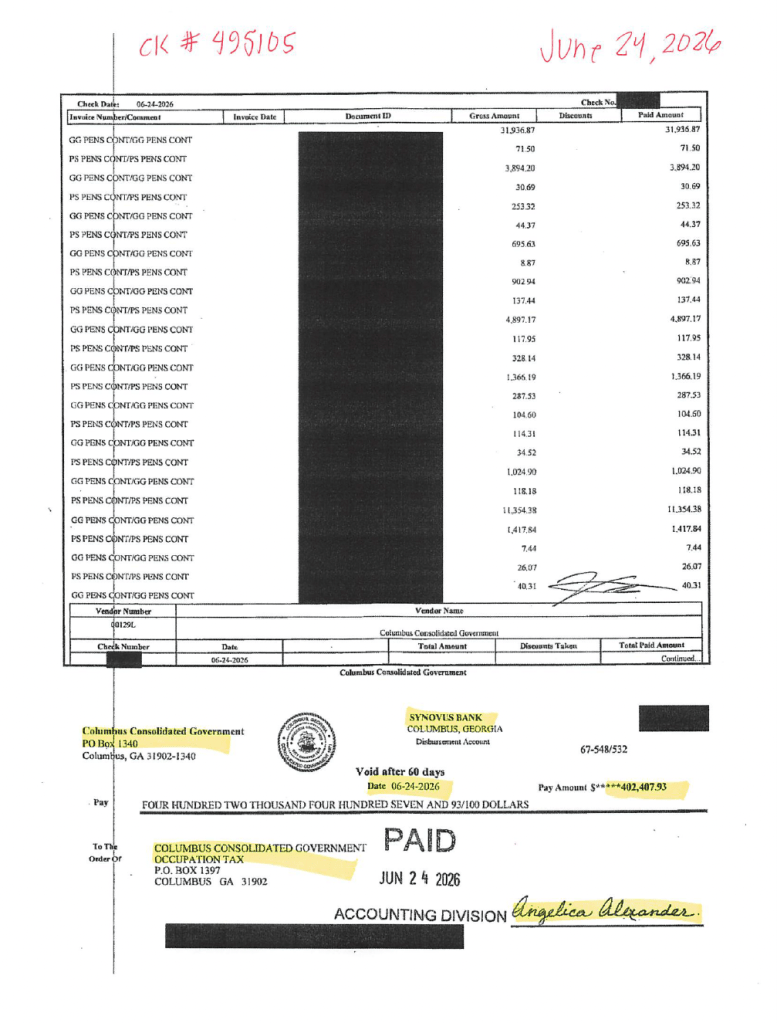
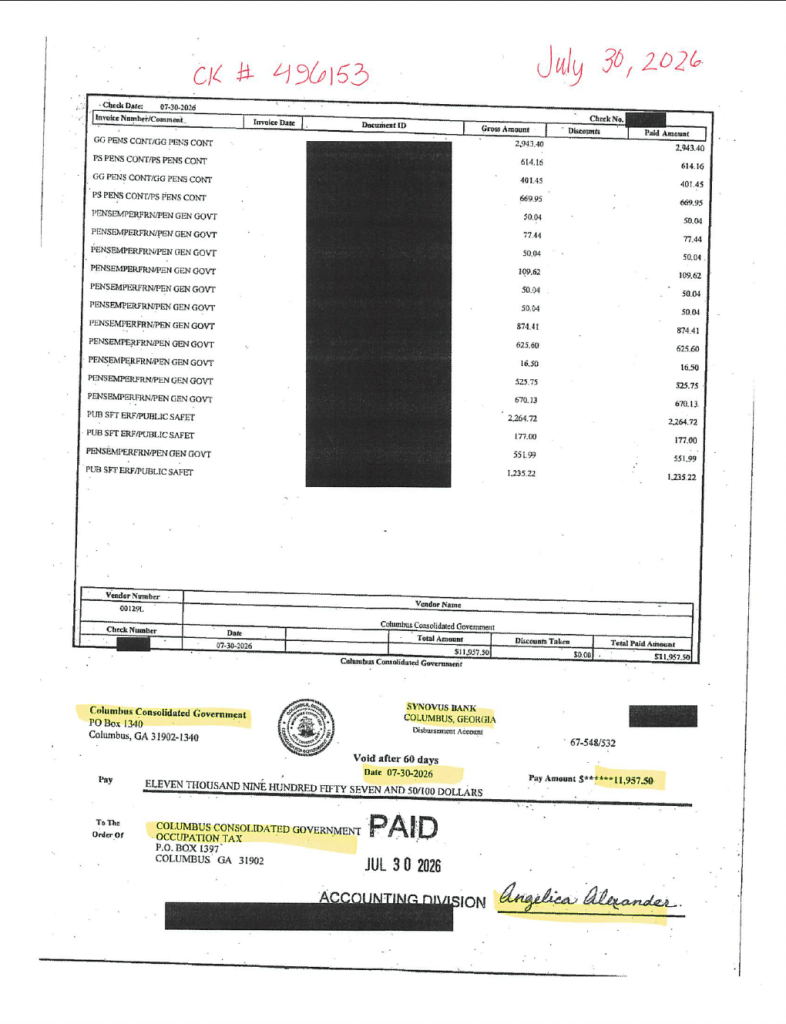
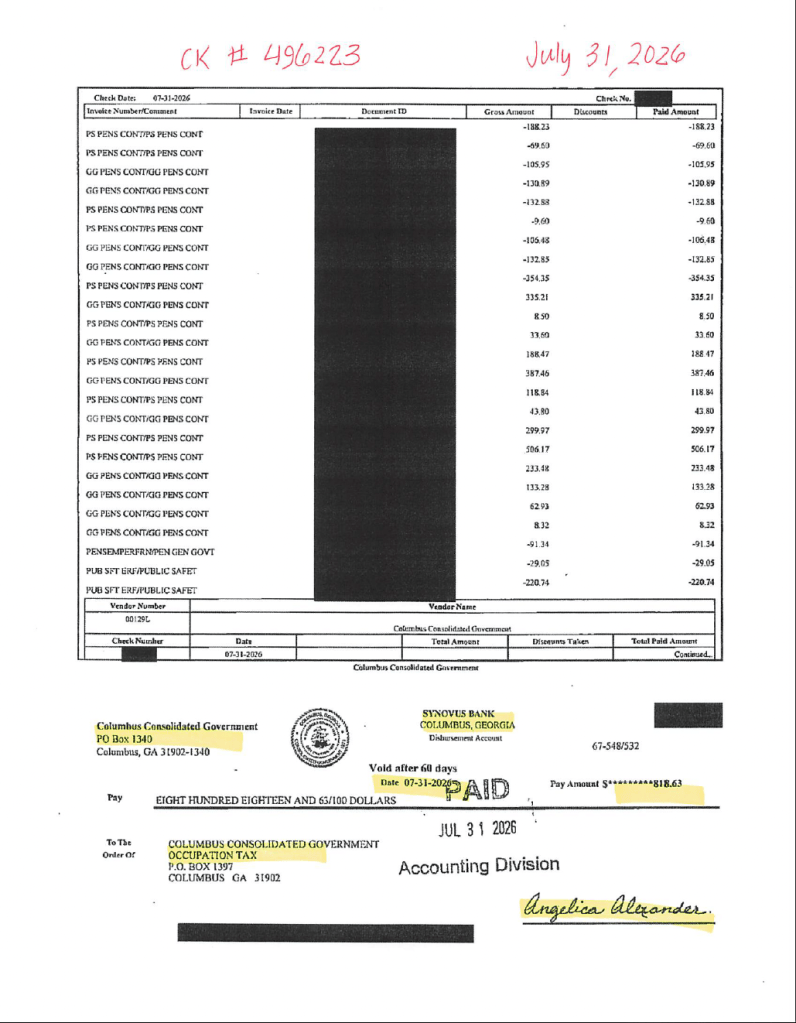
In the “Pay to the Order of” field of each check, “Columbus Consolidated Government Occupation Tax” is listed. Angelica Alexander‘s name is on the signature line of these checks, the dates the checks were written, and the amount of each check.
What you won’t see is the document ID, which has been redacted. Is this the employee information that shows whose account the disbursement was made from? You also won’t see the check number, which they have also redacted; however, Guy must have forgotten to rename the files and they were named after the check number, so the check number is written in red at the top left of each check.
Keep in mind that this is just the first page of each of the 41 checks that is presented below.
The entirety of each check is available for your review via Google drive. For now, let us review the checks below.
THE 41 CHECKS
These checks have been provided by date. There are checks that run parallel with payroll and some checks that seem to randomly occur, and your guess as to why is best.
January 8, 2026
January 21, 2026
January 26, 2026
January 29, 2026
February 4, 2026
February 18, 2026
February 19, 2026
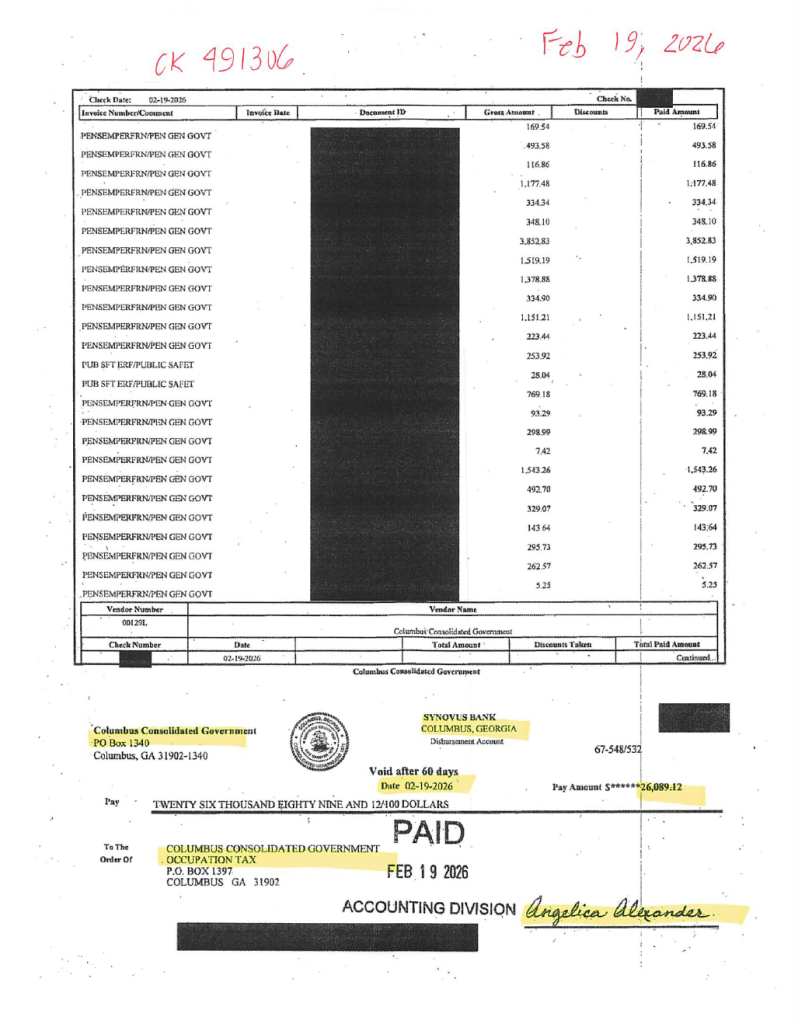
February 26, 2026
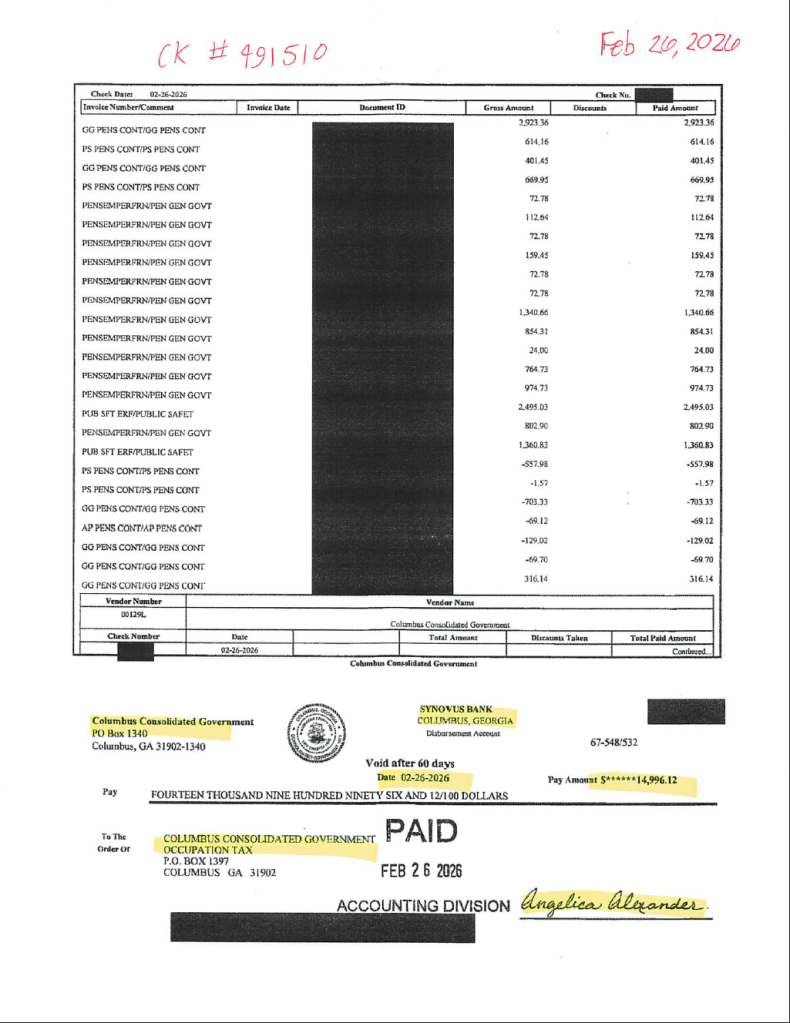
March 4, 2026
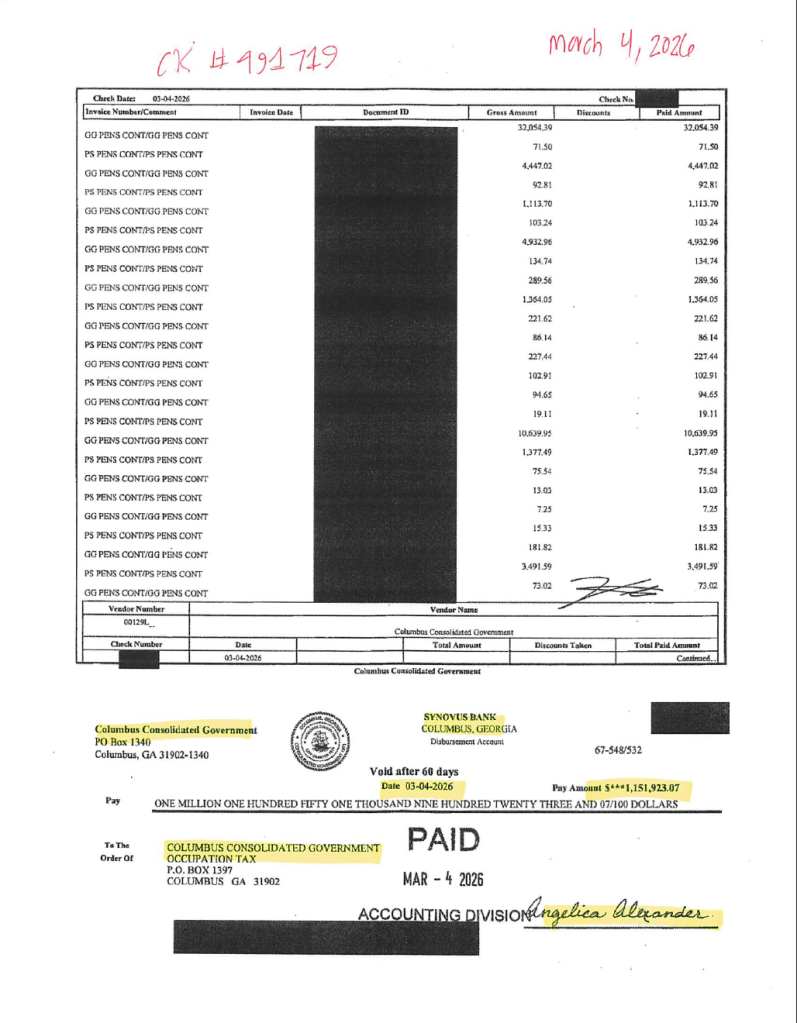
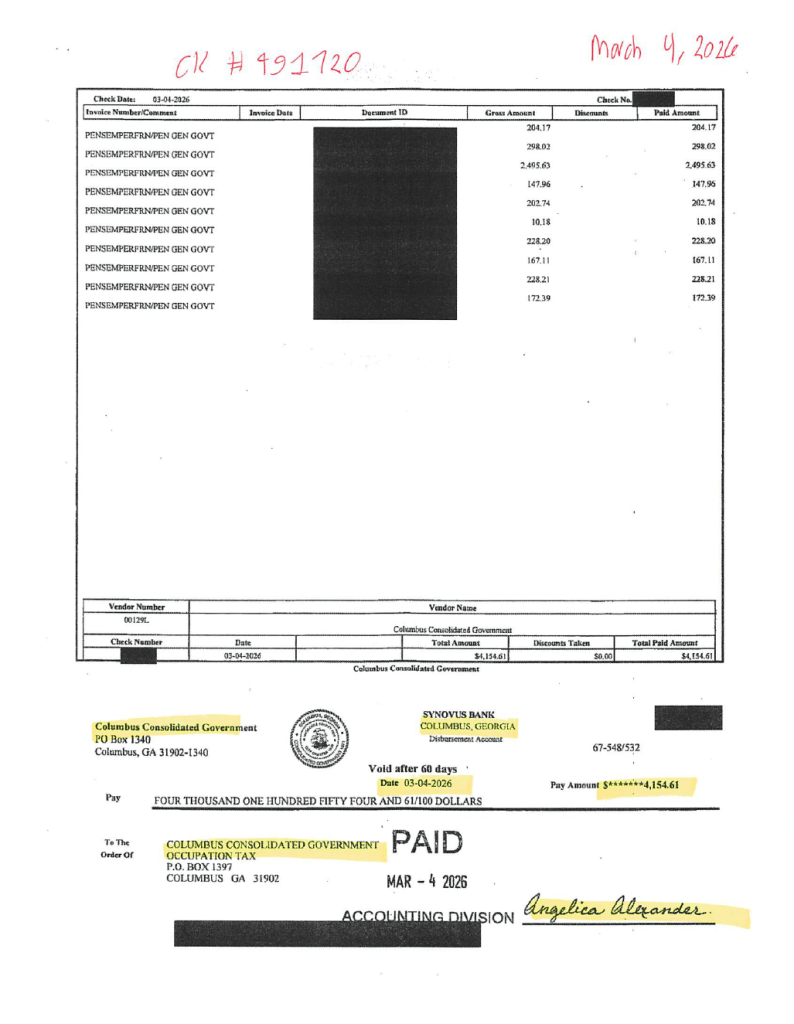
March 18, 2026
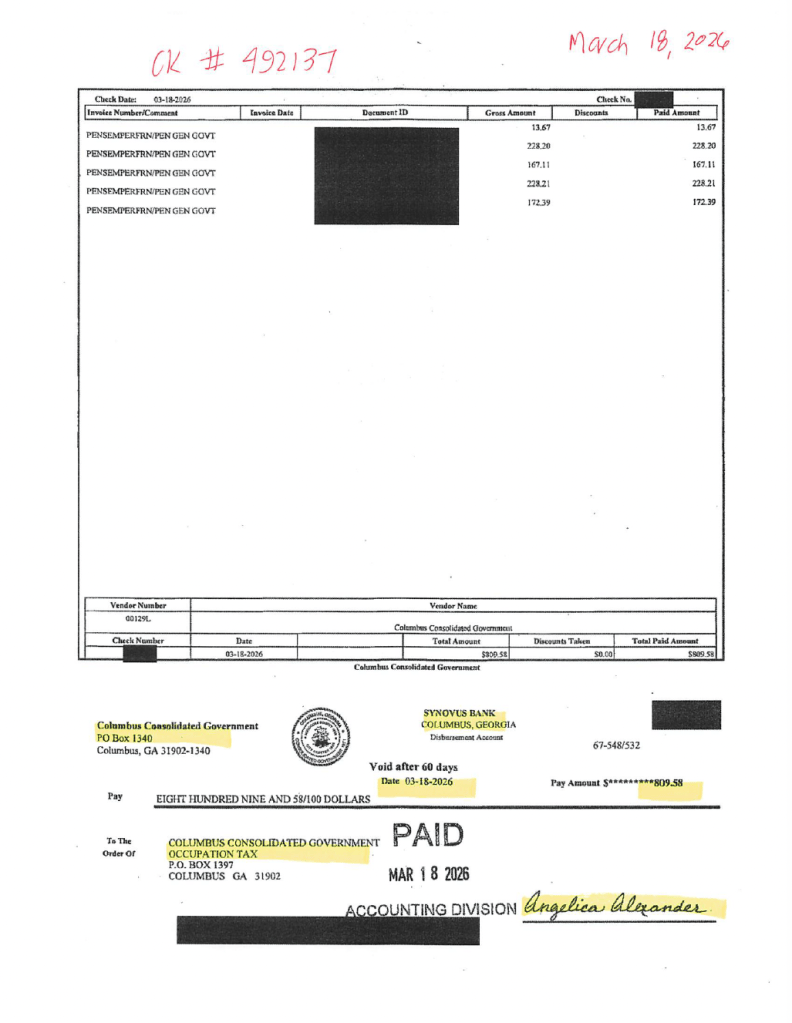
March 30, 2026
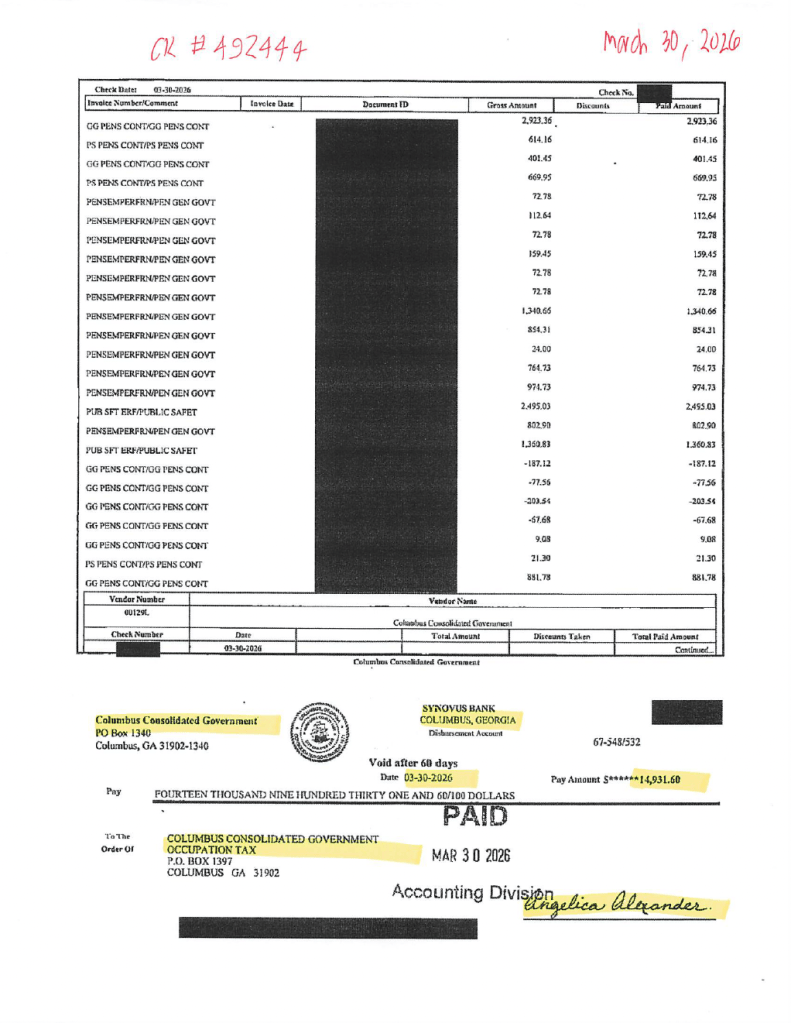
April 1, 2026
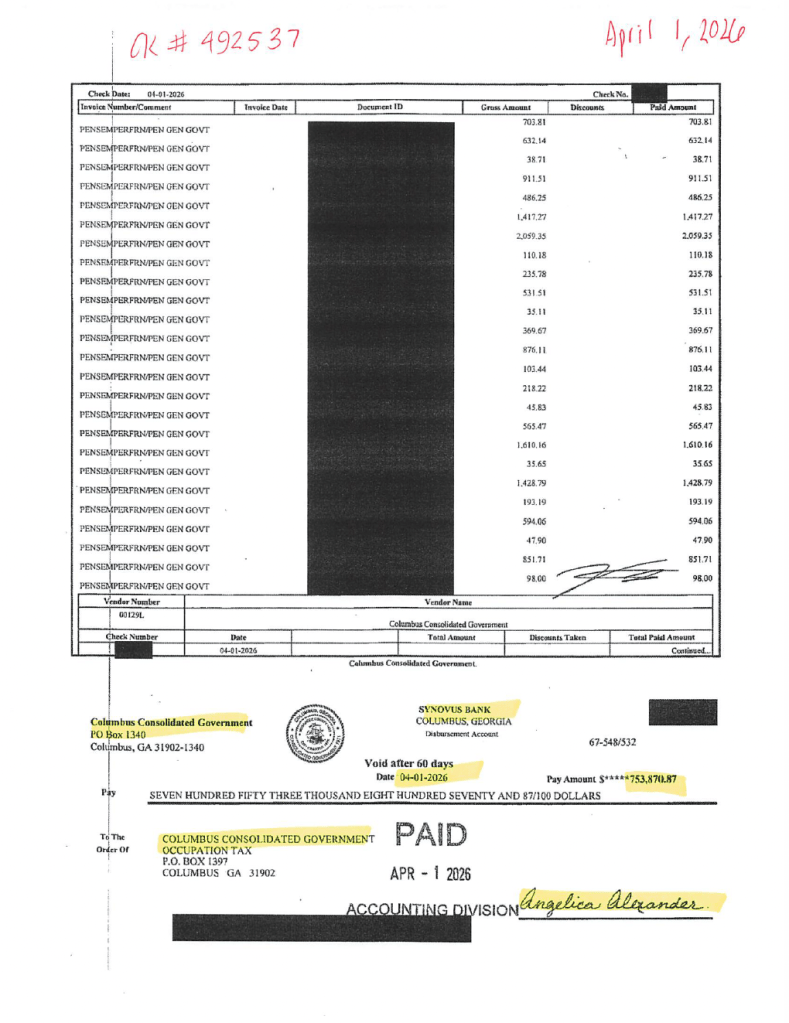
April 3, 2026
April 15, 2026
April 24, 2026
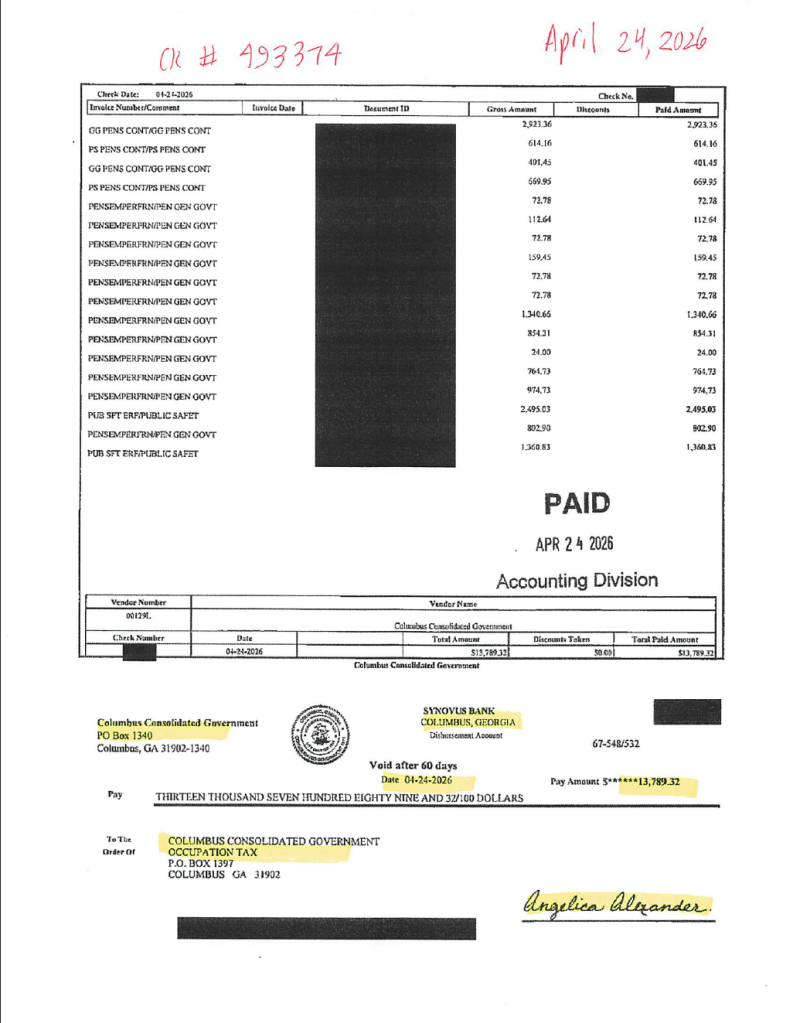
April 27, 2026
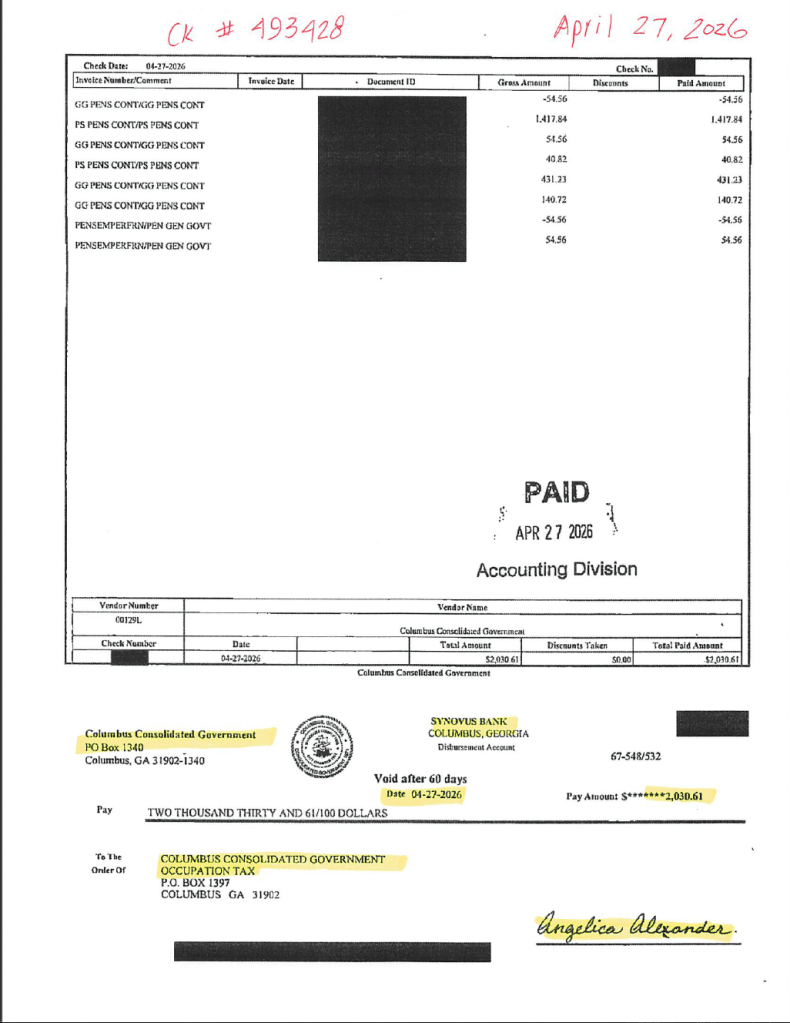
May 1, 2026
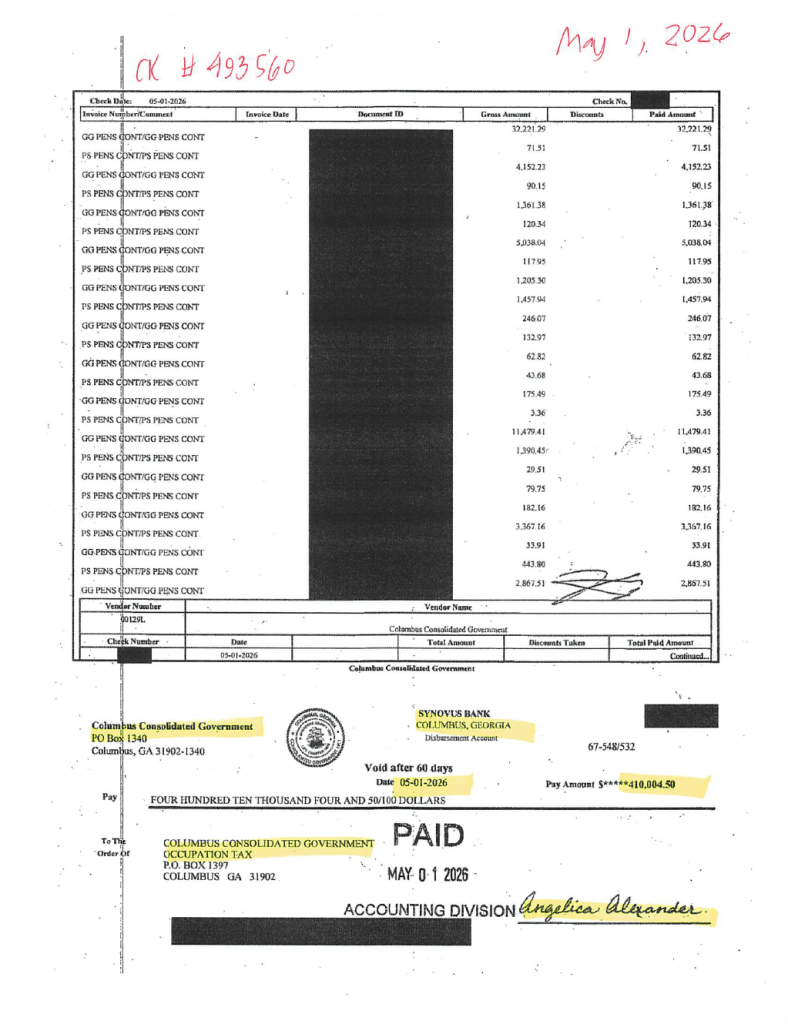
May 4, 2026
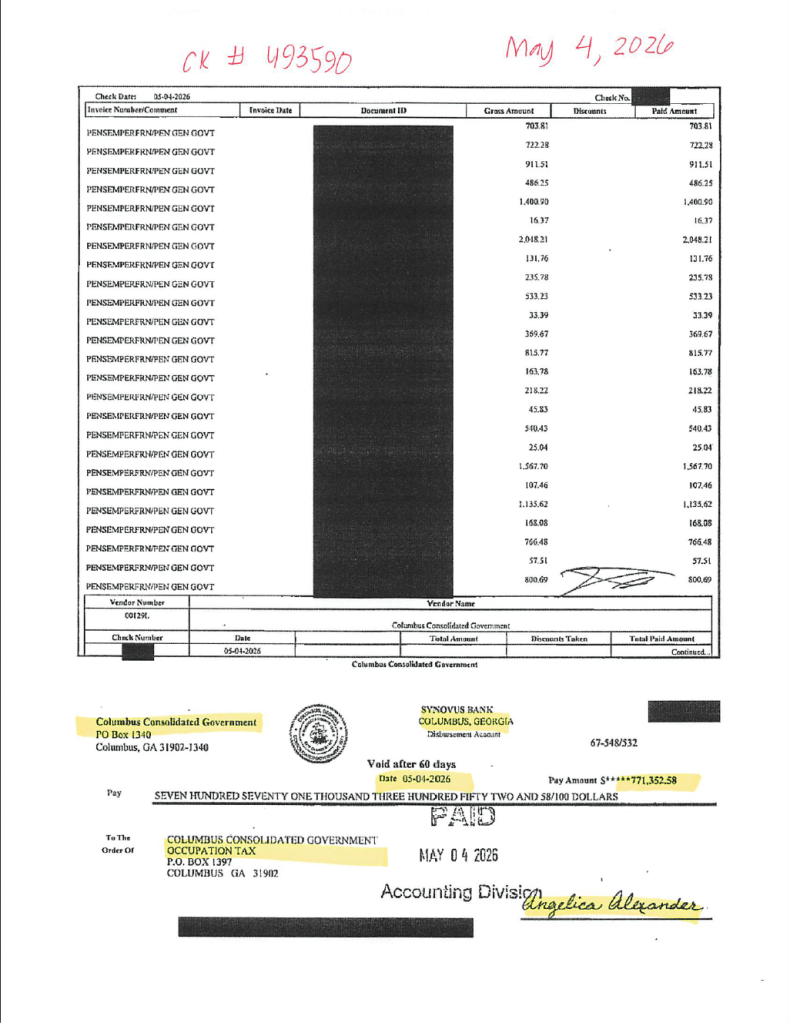
May 13, 2026
May 22, 2026
May 28, 2026
June 10, 2026
June 24, 2026
June 29, 2026
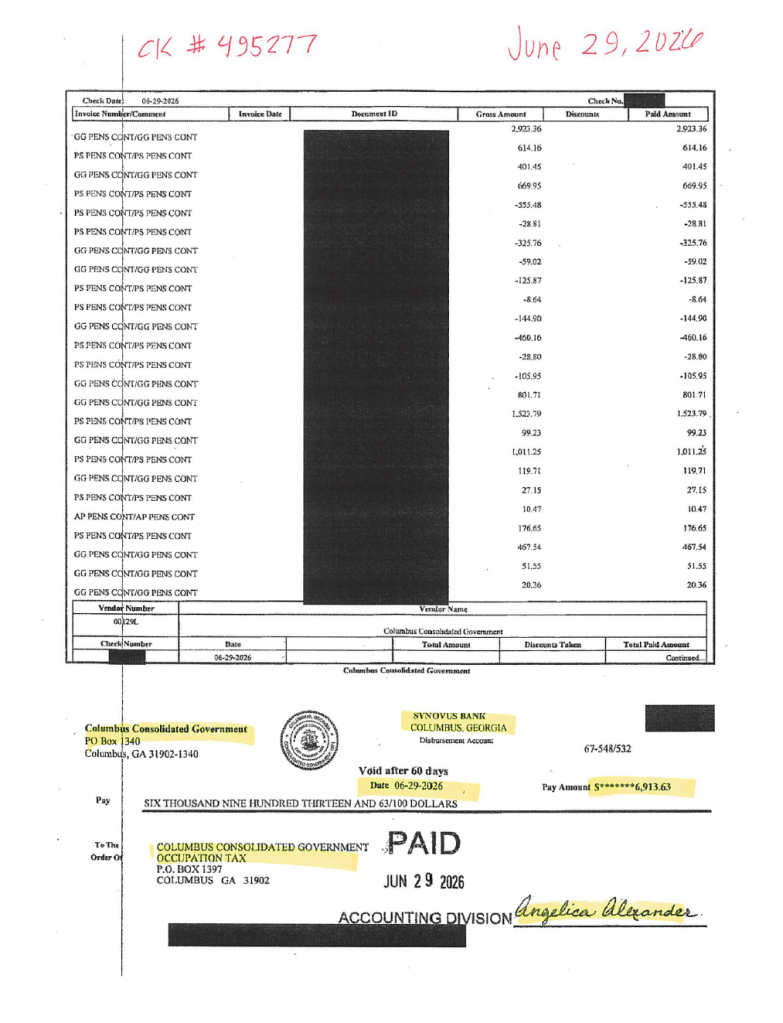
July 8, 2026
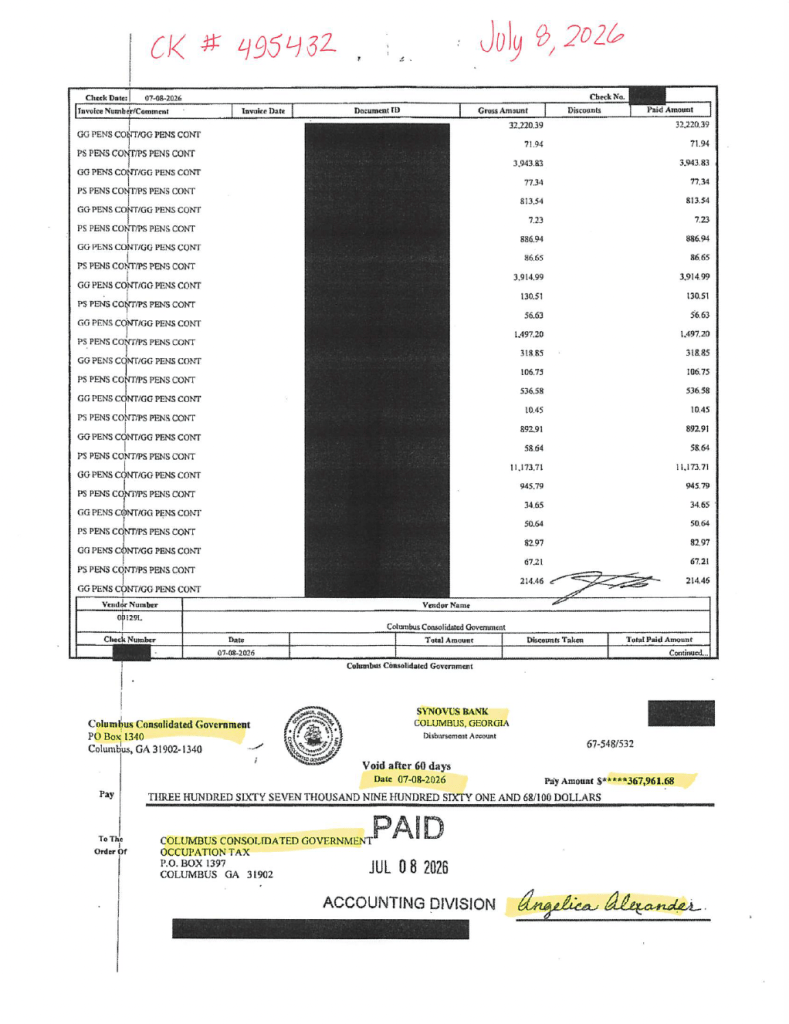
July 22, 2026
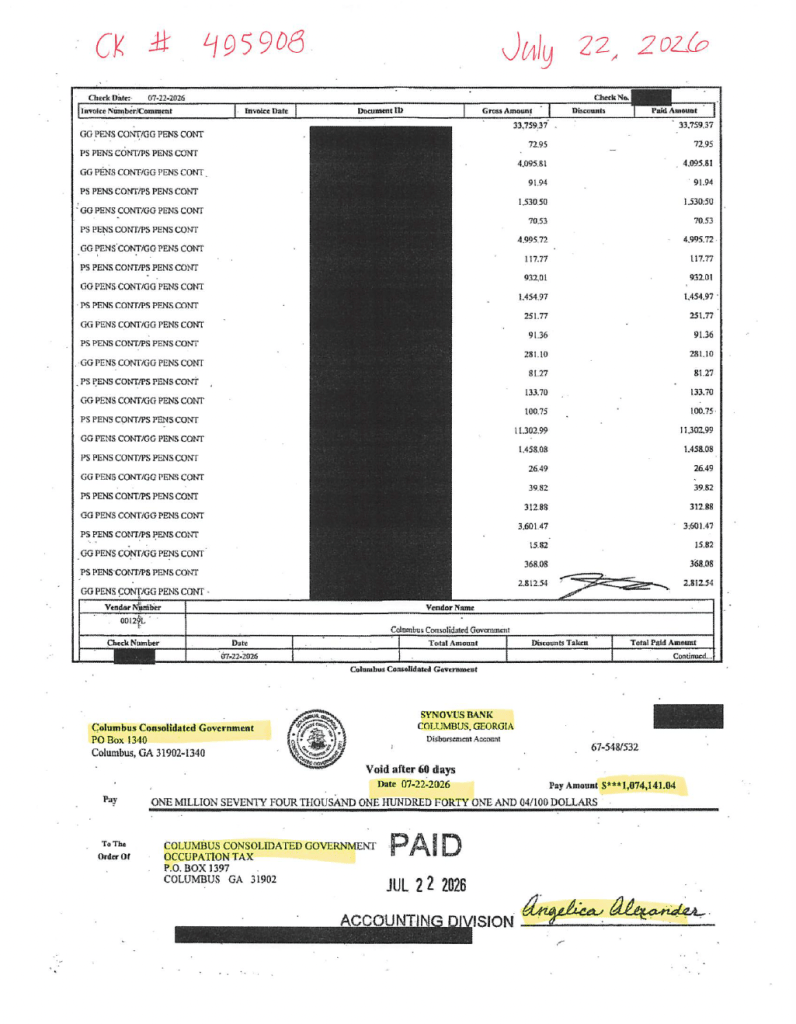
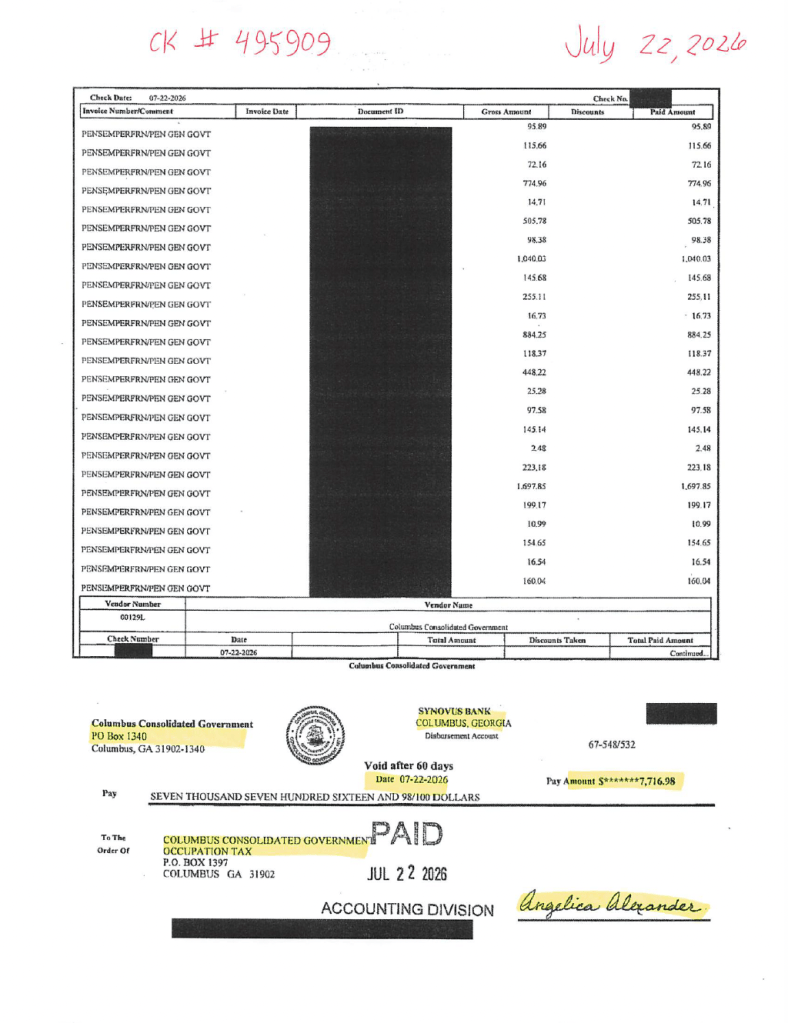
July 30, 2026
July 31, 2026
THE $16.1 MILLION DISBURSEMENT
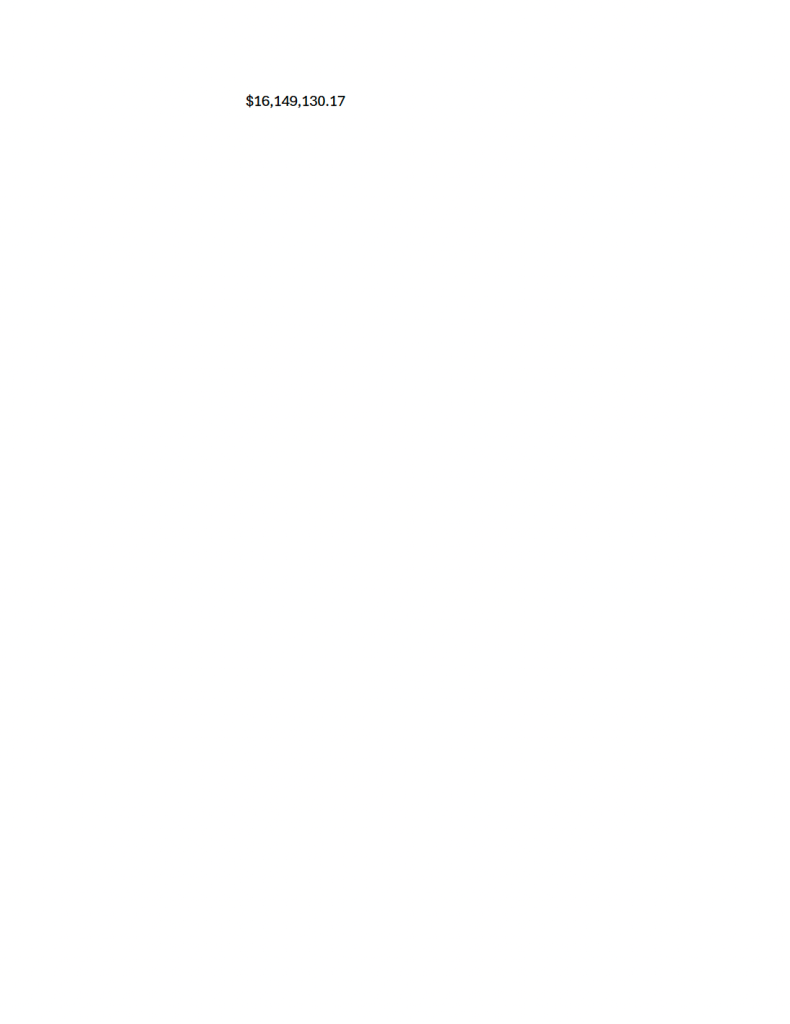
By placing each of the 41 checks by date, number, and amount in Excel, I used AutoSum to calculate the total amount of disbursements from the Employee Pension Fund (labeled Disbursement Account on each check) and made Payable to the Occupational Tax Account. The total amount of disbursements from January to August 5, 2026 is $16,149,130.17.
THE TOP 89
After going through all of the checks, and their multitude of transactional pension disbursements, it was time to compile “The Top 89.” What are “The Top 89 you ask?” They are the top 89 largest amounts that were disbursed from employees’ pension funds to the occupational tax account. These are by far, not the only large single disbursements. There are more! You can view those by date in the Excel Workbook that has been compiled where you can review them by check later in this publication.
The lowest of the “The Top 89” is $30,094.60 and the highest is $117,544.16. Keep in mind there are some disbursements that are less than $1 as well.
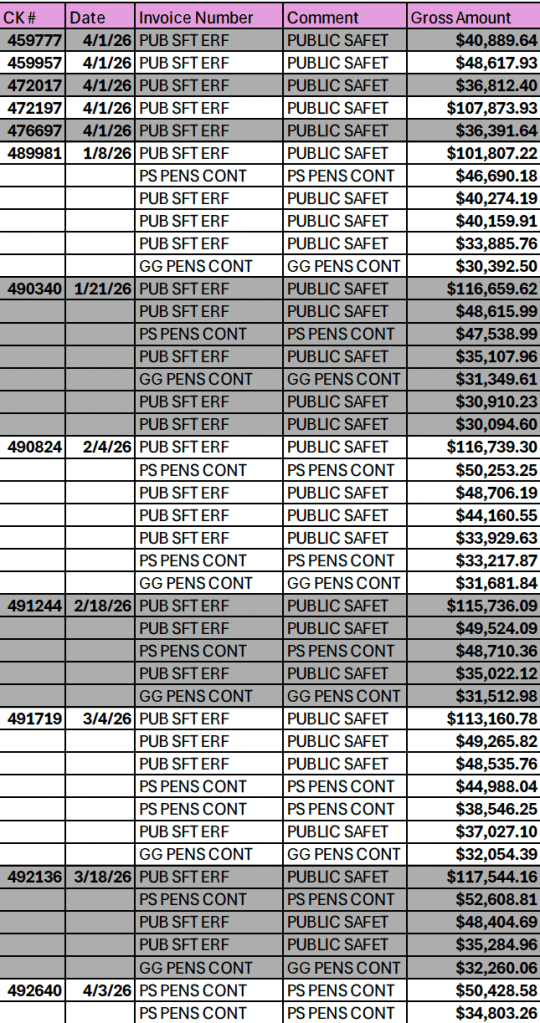
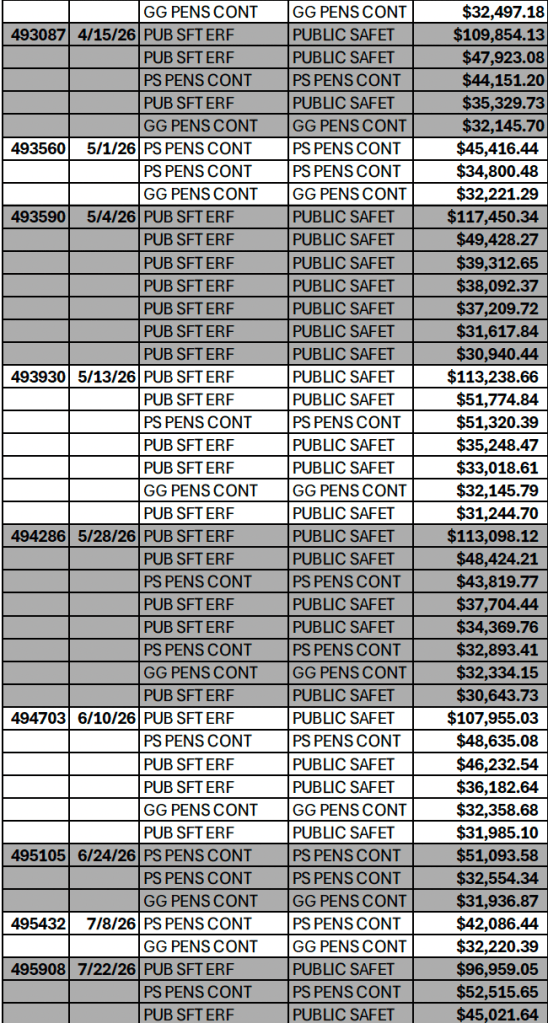
A few questions came to mind.
- Why were such large amounts being withdrawn from an employee’s pension account?
- Did the higher withdrawals come from employees who had been employed with the Columbus Consolidated Government a longer time than the ones where smaller amounts were taken?
- Were these employees using their pension money to pay their business licenses?
- Were these employees paying their penalties and taxes for taking money out of their pensions before vesting or retirement?
- Did these employees even know their money was being taken out of their pension fund?
- How can these pension funds draw interest if they weren’t being invested?
THE CRITICAL ISSUE
The critical issue is that employee money is allegedly being taken out of their pension accounts, with or without their knowledge, sometimes in the hundreds of thousands per withdrawal, and sometimes in the millions of dollars per check, and placed in an account designated for business licenses and business taxes. Considering this account has been related to a previous investigation, it would have been wise to use a different account altogether, but I digress.
The critical issue is that Angelica Alexander, the Director of Finance, and the one who has signed these checks, was recorded at the city council meeting on July 22, 2025, telling the council members that there was $660 Million sitting in the Employee Pension Fund Account.
The critical issue is that Angelica Alexander said that the Pension Fund has its own fund and its own account. In fact, she said that multiple times.
The critical issue is that Angelica Alexander then told that very same council that there was “NO COMMINGLING.”
The critical issue is that Angelica Alexander told that very same council that when the pension payments came out of the employees’ payroll checks, they went directly into the pension fund.
That means there is no account in between.
Why did Angelica Alexander feel the need to tell the council over and over that the pension fund had it’s own account? Why did Angelica Alexander feel that she had to offer, without being asked, that there was no commingling? Was it her guilty conscience? Was she simply attempting to quell concerns that may have already mounted? Did she feel she had to walk on eggshells because she knew that this money was going into the occupational tax account where she was arrested due to the investigation into the city’s business license debacle and she didn’t want to draw any further attention?
PENSION FUND PETTY CASH?
Angelica Alexander stated, “Sometimes we may need cash from the investments to cover some of the outflows we have for the um for the plan and that’s just you know sometimes there’s a cashflow need um its a timing issue where we receive the monies from the component units and from the bi-weekly payroll process, we may have more going out in a particular month um and we may need some cash from our investments.”
Doesn’t it sound like she is saying that they are using the investment from the employers and employees to cover things they don’t have the ability to pay? Why does she say “um” so much? Why does she say that there’s a cashflow need sometimes and reference using the cash from their investments? If they’re using money from the pension fund to cover their cash flow needs and the “outflows” that occur during the month when more money is going out than coming in, doesn’t that sound like they’re using the employee money as a personal petty cash fund? And if they’re taking employee pension money out to do that to cover outflows, why is the occupational tax account not listed as an outflow in her presentation? If they’re using the investments from payroll and employer contributions, doesn’t that defeat the purpose of an investment? Are they paying taxes on those withdrawals? Can employees have confidence that they haven’t been working so many years for CCG and they have a nice nest egg to retire on?
UNDER WHOSE AUTHORITY?
The last question that needs to be asked, is whose authority did Angelica Alexander use to issue all of these checks? Many people might could say it was Isaiah Hugley, but let me remind everyone that these checks were written from January 2026 to August 5, 2026. Isaiah Hugley was terminated as the city manager on May 27, 2025 by a majority vote of the council. So, we cannot with certainty say he had anything to do with what Angelica Alexander has done. So, did Angelica Alexander act in her own authority?
IN CLOSING
Angelica Alexander, in her own words, and by her own signature, has provided multiple pieces of evidence that provide what’s called probable cause in the legal world. There’s enough evidence that has been presented that could very well support employee pension funds being misused, being misdirected, being misappropriated, being commingled, being disbursed without an employee’s knowledge, and as our inside city employee said, it appears that they are “robbing Peter to pay Paul.”
What do you think? If you’re an employee have you checked your pension account? Does it show that you have earned any interest? Did you know that if you walk away before you’re vested you can opt to take a lump sum of your own money? Will there be any money for you to use if it’s being used to pay the city’s bills?
Make sure to check out the checks in their entirety, the excel workbook I compiled, and the entire video from the council meeting on July 22, 2025, where Angelica Alexander speaks in detail about the Pension Fund. If you have any questions, feel free to contact me at plumblyneproductions@gmail.com or 229-329-2179. In the meantime, y’all stay safe out there.


Leave a Reply